Ceramic Substrates Market Size & Growth Forecast 2027–2036, By Segments (Product Type, End Use), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Ceramic Substrates Market size was worth USD 10.36 Billion in 2026 and is expected to grow at 10.6% CAGR between 2027 and 2036, surpassing USD 28.37 Billion by 2036. The industry revenue for 2027 is assessed at USD 11.29 Billion.
Get more details on this report
Request Free Sample ReportCeramic Substrates Market Intelligence Snapshot
Regional Market Dynamics
- Asia Pacific led in 2026, supported by extensive electronics manufacturing and strong demand from semiconductor, telecommunications, automotive electronics, and power electronics industries.
- North America is expanding rapidly through domestic semiconductor investment, advanced electronics deployment, electrified vehicles, renewable energy systems, and resilient supply-chain initiatives.
Segment Momentum
- Alumina accounted for 59.04% of the market in 2026 because it combines electrical insulation, thermal stability, mechanical strength, and cost efficiency, making it suitable for high-volume electronic and industrial applications.
- The automotive segment is the fastest-growing as vehicle electrification, advanced driver assistance systems, and expanding electric vehicle adoption increase demand for high-performance ceramic substrates.
Market Expansion Drivers
- Rising electronics industry demand driving adoption of high-performance ceramic substrates
- Advancements in 5G infrastructure accelerating demand for high-frequency electronic components
- Increasing medical device miniaturization boosting ceramic substrate usage in diagnostics equipment
Leading Market Participants
- Major players in the ceramic substrates market include Kyocera Corporation (Japan), Murata Manufacturing Co., Ltd. (Japan), CoorsTek, Inc. (United States), CeramTec GmbH (Germany), NGK Insulators, Ltd. (Japan), MARUWA Co., Ltd. (Japan), Rogers Corporation (United States), Chaozhou Three-Circle (Group) Co., Ltd. (China), Tong Hsing Electronic Industries, Ltd. (Taiwan), KOA Corporation (Japan)
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 10.36 Billion
- 2027 Estimated Market Size: USD 11.29 Billion
- Projected Market Size: USD 28.37 Billion by 2036
- Growth Forecast: 10.6% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Asia Pacific
- High-Growth Regional Hub: North America
- Core Revenue Segment: Alumina (Product Type) | Consumer Electronics (End Use)
- Emerging Opportunity Segment: Aluminum Nitride (Product Type) | Automotive (End Use)
Market Growth Drivers and Industry Trends
Rising electronics industry demand driving adoption of high-performance ceramic substrates
The rapid expansion of consumer electronics, industrial electronics, automotive electronics, and power devices is creating sustained demand for advanced materials, which will drive the ceramic substrates market growth. Ceramic substrates provide excellent thermal conductivity, electrical insulation, and mechanical stability, making them well suited for high-performance electronic assemblies operating under demanding conditions. As electronic devices become more compact and power-intensive, manufacturers increasingly rely on ceramic substrate technologies to improve heat dissipation, enhance reliability, and support the long-term performance of sophisticated semiconductor and circuit packaging applications.
Advancements in 5G infrastructure accelerating demand for high-frequency electronic components
The global deployment of next-generation communication networks is increasing the need for components capable of operating at higher frequencies with minimal signal loss, supporting the expansion of the ceramic substrates market. Ceramic substrates are widely utilized in radio frequency modules, antennas, power amplifiers, and communication equipment because of their favorable dielectric properties and thermal performance. As telecommunications infrastructure evolves to accommodate greater data transmission speeds and network capacity, demand continues to grow for substrate materials that enable stable operation in increasingly complex electronic environments.
Increasing medical device miniaturization boosting ceramic substrate usage in diagnostics equipment
Medical device manufacturers are developing increasingly compact diagnostic systems without compromising accuracy or reliability, a trend that will propel the ceramic substrates market growth. Miniaturized medical electronics require substrate materials capable of supporting dense circuit integration while maintaining electrical insulation, dimensional stability, and efficient thermal management. Ceramic substrates help enable the production of advanced diagnostic instruments, wearable medical technologies, and precision healthcare equipment by providing dependable performance in applications where long-term reliability and component integrity are essential.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Rising electronics industry demand driving adoption of high-performance ceramic substrates | 2% | Moderate | Asia Pacific, North America | High | Near Term |
| Advancements in 5G infrastructure accelerating demand for high-frequency electronic components | 1.8% | Moderate | Asia Pacific, Europe | High | Near Term |
| Increasing medical device miniaturization boosting ceramic substrate usage in diagnostics equipment | 1.5% | High | North America, Europe | Medium | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
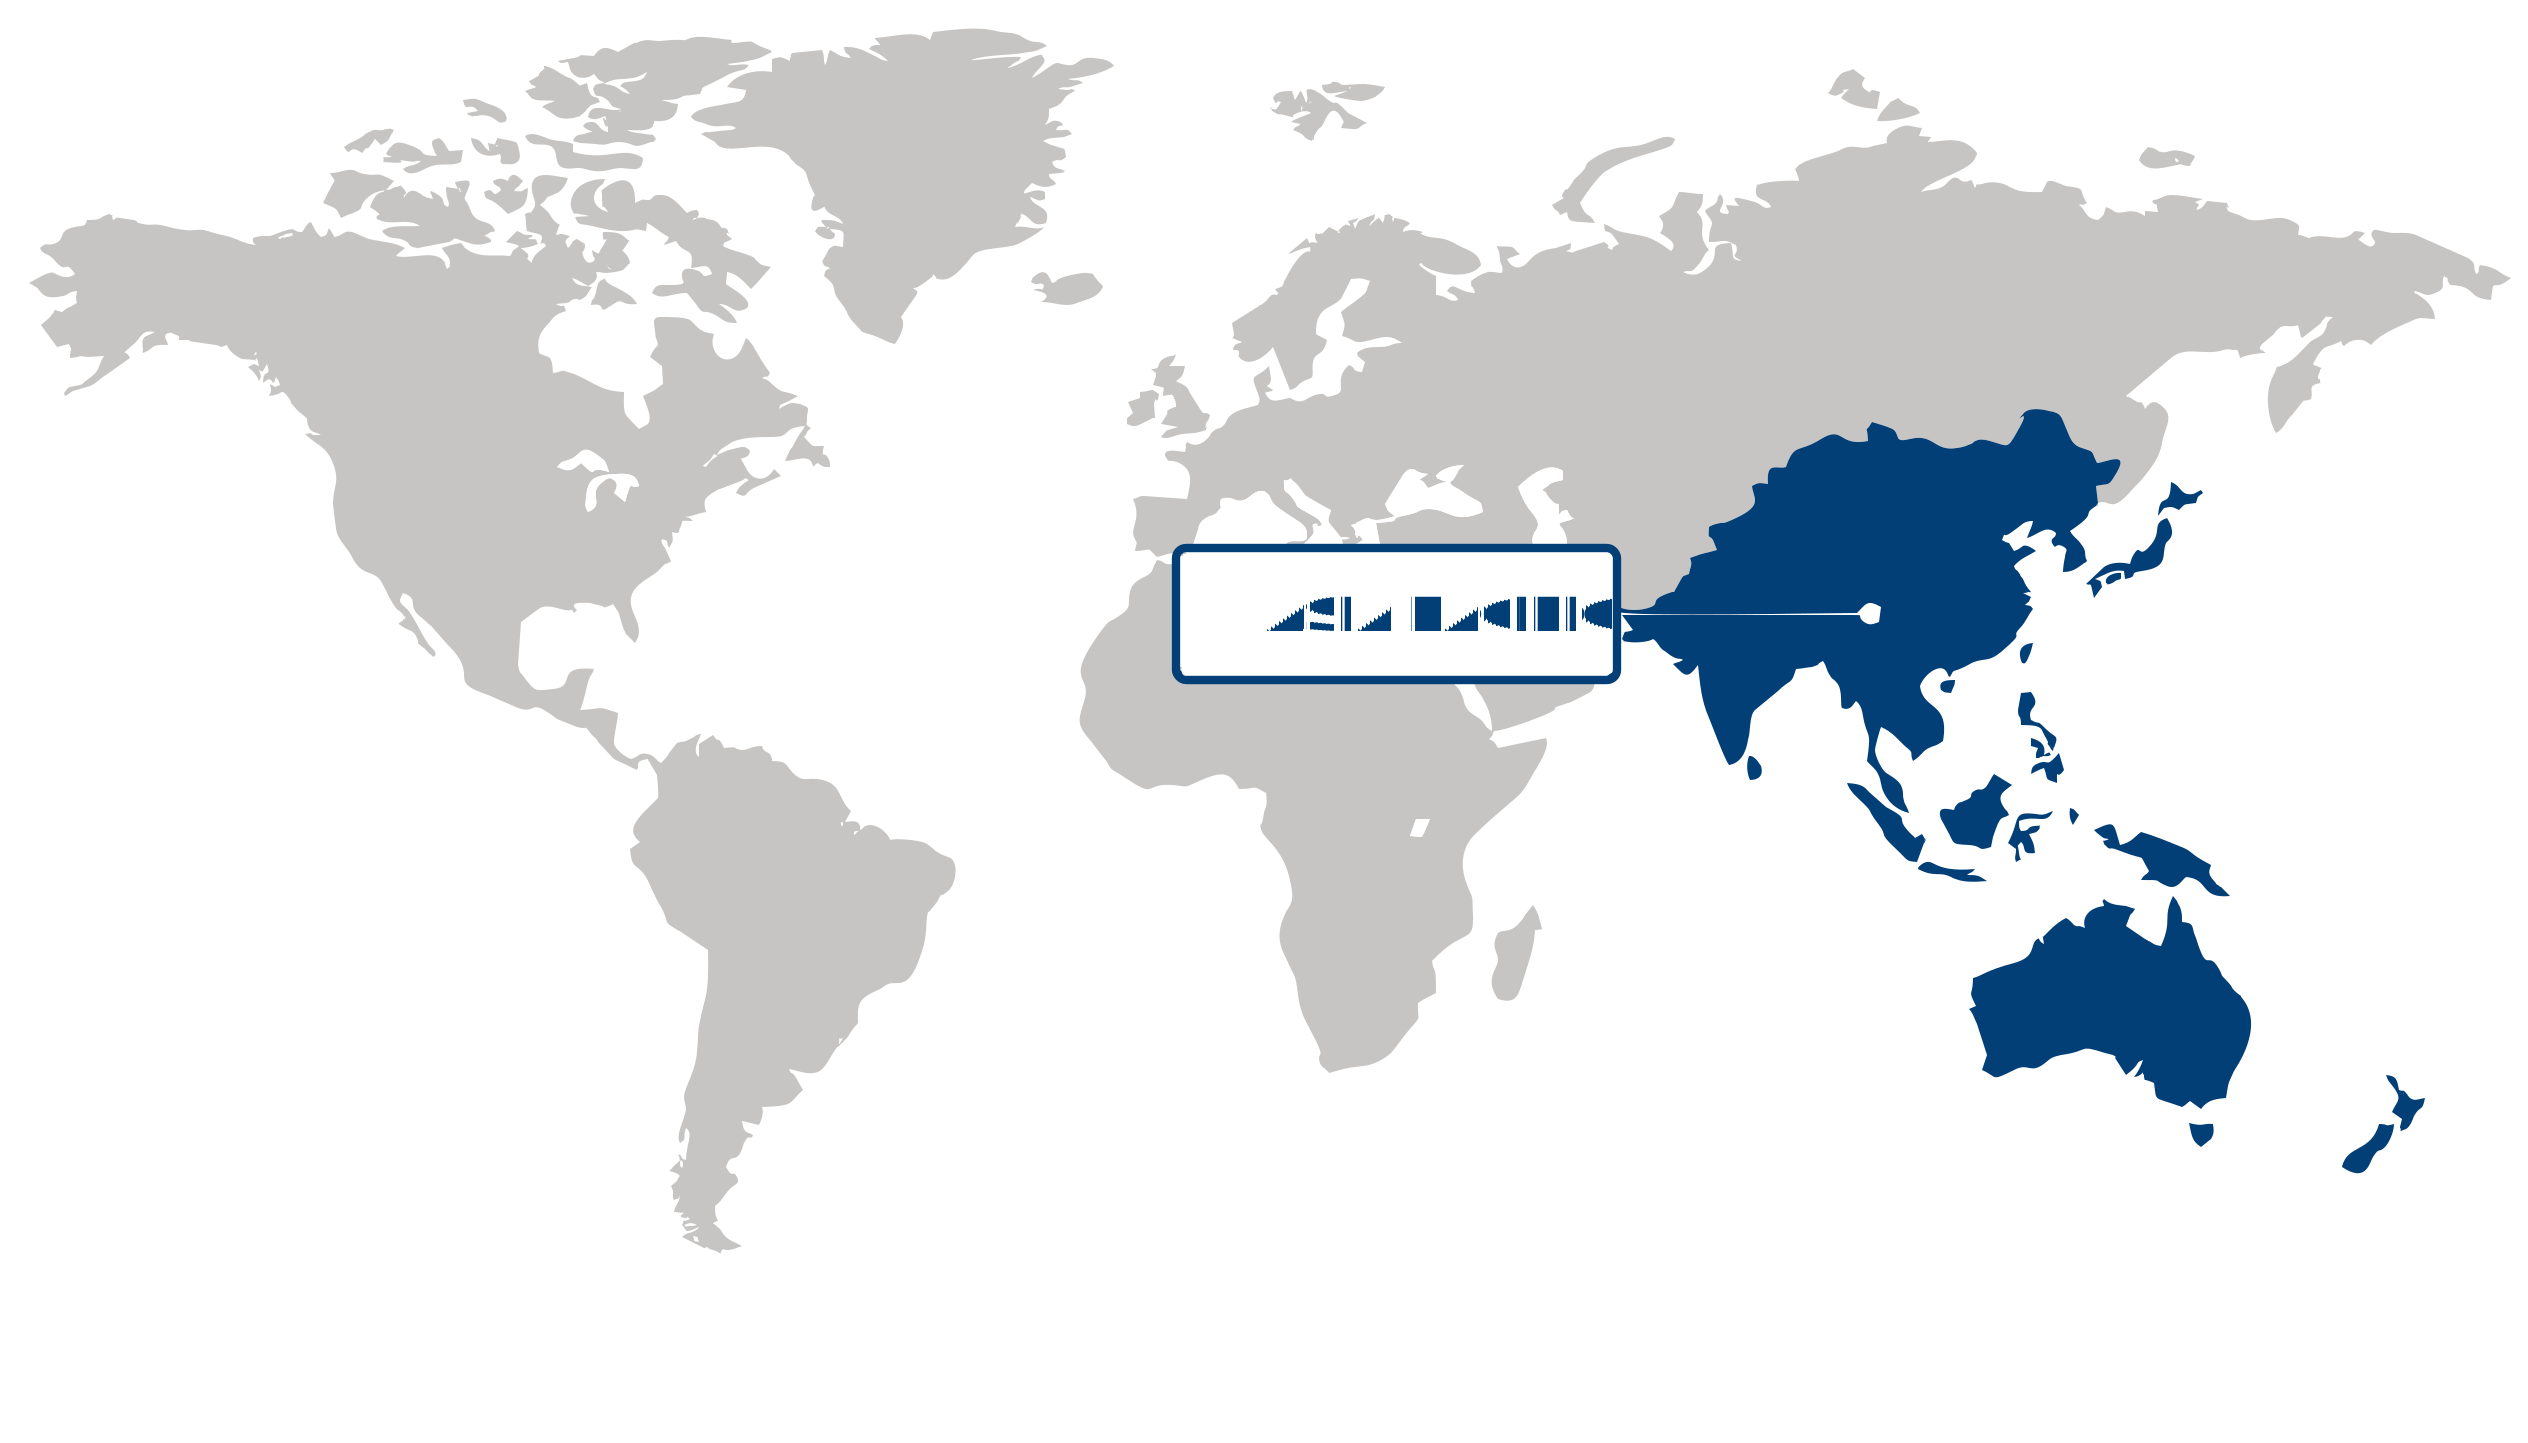
Asia Pacific (Largest Region)
The Asia Pacific ceramic substrates market held the largest position in 2026, benefiting from the region’s extensive electronics manufacturing base and strong demand for components that support efficient thermal management and electrical performance. The expansion of semiconductor, power electronics, telecommunications, and automotive electronics production is increasing the need for reliable substrate materials capable of handling demanding operating conditions. Growing investments in advanced electronics manufacturing and the transition toward higher-performance components are further supporting the use of ceramic substrates. In addition, the region’s integrated manufacturing ecosystem and expanding applications for electronic power-management systems continue to reinforce its market position.
North America (Fastest-Growing Region)
North America is experiencing the fastest growth in the ceramic substrates market as demand for advanced electronics, power management systems, and high-performance semiconductor technologies expands. Increasing investment in domestic semiconductor and electronics manufacturing is creating opportunities for substrate technologies that provide strong thermal conductivity, electrical insulation, and reliability. The growing deployment of electric and electrified vehicles, renewable energy systems, and advanced computing infrastructure is also broadening the need for efficient power-electronic components. Greater emphasis on resilient technology supply chains and advanced manufacturing capabilities is further supporting regional demand for ceramic substrate solutions.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
United States 🇺🇸
High-Performance ElectronicsThe U.S. ceramic substrates market is driven by demand from advanced electronics, power devices, and semiconductor applications requiring reliable thermal performance. Manufacturers emphasize materials that support higher efficiency and long-term operational stability.
Germany 🇩🇪
Industrial Power ApplicationsGermany prioritizes ceramic substrates for industrial electronics, automotive power modules, and precision manufacturing applications. Companies focus on high-quality substrate solutions that improve heat management and component durability.
Japan 🇯🇵
Precision Materials DevelopmentJapan advances ceramic substrates through continuous materials innovation for electronics, semiconductor packaging, and high-reliability components. Manufacturers emphasize consistent product quality and performance for demanding industrial applications.
South Korea 🇰🇷
Semiconductor Supply SupportSouth Korea strengthens ceramic substrate demand through semiconductor manufacturing and advanced electronic component production. Companies invest in substrate technologies that enhance thermal performance while supporting increasingly compact device designs.
France 🇫🇷
Electronics Manufacturing SupportFrance focuses on ceramic substrates for industrial electronics and specialized electrical applications requiring dependable thermal and mechanical characteristics. Manufacturers seek material solutions that improve product reliability across high-value applications.
Italy 🇮🇹
Specialty Component ProductionItaly utilizes ceramic substrates across industrial equipment, power electronics, and specialized manufacturing applications. Producers emphasize durable substrate materials that support efficient production processes and dependable performance in demanding operating environments.
Ceramic Substrates Market Share (%), by Product Type, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportProduct Type Segment Analysis: Alumina (Largest Segment) vs Aluminum Nitride (Fastest-Growing Segment)
The ceramic substrates market was led by the alumina segment, which accounted for 59.04% in 2026. Alumina substrates are extensively used because they provide an effective balance of electrical insulation, mechanical strength, thermal stability, and cost efficiency, making them suitable for a broad range of electronic and industrial applications. Their widespread availability, well-established manufacturing processes, and compatibility with high-volume production have supported sustained demand across multiple industries, reinforcing the segment's dominant position.
The aluminum nitride segment is expected to experience the fastest growth, driven by increasing demand for materials with superior thermal conductivity in advanced electronic systems. As electronic devices become more compact and power-dense, manufacturers are increasingly adopting aluminum nitride substrates to improve heat dissipation and operational reliability. Expanding applications in high-performance electronics, electric mobility technologies, and advanced semiconductor packaging continue to create favorable growth opportunities for the segment.
End Use Segment Analysis: Consumer Electronics (Largest Segment) vs Automotive (Fastest-Growing Segment)
The consumer electronics segment accounted for the largest share of 38.02% in 2026, supported by extensive use of ceramic substrates in smartphones, computers, wearable devices, and other electronic products. These substrates play a critical role in ensuring electrical insulation, efficient thermal management, and reliable circuit performance in compact electronic assemblies. Continuous innovation in consumer electronic devices and rising demand for high-performance components continue to sustain the segment's leadership.
In the ceramic substrates market, the automotive segment is projected to register the fastest growth due to increasing integration of advanced electronic systems in modern vehicles. The expanding adoption of electric vehicles, advanced driver assistance systems, and vehicle electrification has heightened demand for ceramic substrates capable of delivering reliable thermal performance and long-term durability. Ongoing technological advancements in automotive electronics are expected to further accelerate growth across this end-use segment.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Product Type | Alumina, Aluminum Nitride, Silicon Nitride, Beryllium Oxide, Others | Alumina | Aluminum Nitride |
| End Use | Consumer Electronics, Aerospace and Defense, Automotive, Semiconductor, Telecommunication, Others | Consumer Electronics | Automotive |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Major players in the ceramic substrates market:
- Kyocera Corporation (Japan)
- Murata Manufacturing Co., Ltd. (Japan)
- CoorsTek, Inc. (United States)
- CeramTec GmbH (Germany)
- NGK Insulators Ltd. (Japan)
- MARUWA Co., Ltd. (Japan)
- Rogers Corporation (United States)
- Chaozhou Three-Circle (Group) Co., Ltd. (China)
- Tong Hsing Electronic Industries Ltd. (Taiwan)
- KOA Corporation (Japan)
Demand from high-performance electronics and advanced power applications is reshaping competitive priorities within the ceramic substrates market. Manufacturers are investing in material innovation that delivers superior thermal management, electrical insulation, and mechanical durability while maintaining compatibility with increasingly sophisticated semiconductor packaging technologies. The ability to customize substrate characteristics for specialized industrial, automotive, and communication applications has emerged as a meaningful source of differentiation, encouraging suppliers to strengthen technical collaboration with downstream manufacturers during product development. Competitive positioning is also becoming closely tied to manufacturing precision and production reliability as customers seek consistent quality across increasingly complex electronic systems.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Kyocera Corporation (Japan) | |||||||
| Murata Manufacturing Co. Ltd. (Japan) | |||||||
| CoorsTek Inc. (United States) | |||||||
| CeramTec GmbH (Germany) | |||||||
| NGK Insulators Ltd. (Japan) | |||||||
| MARUWA Co. Ltd. (Japan) | |||||||
| Rogers Corporation (United States) | |||||||
| Chaozhou Three-Circle (Group) Co. Ltd. (China) | |||||||
| Tong Hsing Electronic Industries Ltd. (Taiwan) | |||||||
| KOA Corporation (Japan) |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| SEMI; TechSearch International | Jul-26 | The organizations published the updated Worldwide Assembly & Test Facility Database. The expanded market intelligence tool provides critical data mapping global semiconductor packaging operations that underpin ceramic substrate value chains. |
| CHIPX | Dec-25 | The company announced plans to construct an 8-inch semiconductor and photonics manufacturing plant in Malaysia. This facility expansion scales advanced production capacity to support mounting global demand for high-performance substrate technologies. |
| TSMC | Sep-25 | The semiconductor manufacturer partnered with equipment makers and compound semiconductor firms to co-develop silicon carbide thermal management systems, directly accelerating the evolution of next-generation substrate packaging materials. |
| Huawei | Sep-25 | The technology firm disclosed strategic patents regarding silicon carbide-based thermal management innovations. The proprietary design enhances heat dissipation and electromagnetic shielding in high-performance power electronics and advanced packaging. |
| Orbray | Oct-23 | Following its rebranding from Adamant Namiki Precision Jewel, the firm realigned its operations toward precision engineering, placing capital and strategic focus on advanced zirconia ceramics and sapphire substrates for optical communications. |
| CeramTec | May-23 | The company launched Rubalit ZTA, a high-performance Zirconia Toughened Alumina substrate. This material innovation targets advanced automotive electromobility and power production systems requiring superior thermal and mechanical properties. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Ceramic Substrates Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Metallization Technology | Direct Bonded Copper (DBC), Active Metal Brazing (AMB), Thick-Film Metallization, Thin-Film Metallization |
| Substrate Form Factor | Flat Plates, Multi-Layer Substrates, Custom-Shaped Substrates |
| Customer Type | Semiconductor Manufacturers, Electronic Component Manufacturers, Power Electronics Manufacturers, Contract Electronics Manufacturers |
Ceramic Substrates Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Power Electronics Substrate Roadmap |
|
| EV Thermal Management Opportunity |
|
| Substrate Qualification & Design-In Dynamics |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How much revenue does the ceramic substrates market generate?
How is the ceramic substrates industry size expected to evolve during the forecast period?
How is electronics miniaturization driving demand for ceramic substrates?
Why is 5G infrastructure expansion increasing adoption of ceramic substrates?
Why is alumina the leading product type in the ceramic substrates market?
Which end-use segment is growing the fastest in the ceramic substrates market?
What makes Asia Pacific the leading ceramic substrates market?
Why is North America growing fastest in ceramic substrates?
What are the prominent companies operating in the ceramic substrates landscape?
Our Clients
"Working with FBI has been a good experience. The market report provided a holistic view, covering everything from emerging trends to potential risks."
Semtech Corporation
"The experience was highly positive. The team showcased remarkable flexibility in adapting to our specific needs and delivered report that perfectly aligned with all our requirements."
TSMC
"What really stood out to me was how clearly and promptly the Fundamental Business Insights team communicated throughout. It made the collaboration feel effortless."
NXP Semiconductors
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Electronics & Semiconductors Research Team at Fundamental Business Insights, a dedicated research group specializing in the global electronics and semiconductor ecosystem. Our analysts continuously monitor technology innovations, manufacturing trends, competitive developments, supply chain dynamics, regulatory changes, and end-user demand to deliver timely market intelligence. The research is developed using a structured methodology that combines primary industry interactions, company financial disclosures, government publications, trade associations, technical literature, patent analysis, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook