Market Outlook Snapshot Market Dynamics Regional Forecast Country Insights Segment Analysis Custom Research Competitive Landscape Industry News FAQ
On This Report

Cloud Computing in Energy Market Size & Share, By Service (Infrastructure as a service (IaaS), Platform as a service (PaaS), Software as a service (SaaS)), Platforms (Amazon Web Services (AWS), Microsoft Azure, Google Cloud Platform (GCP), Others), Infrastructure (Servers, Storage, Networking equipment) - Growth Trends, Regional Insights (U.S., Japan, South Korea, UK, Germany), Competitive Positioning, Global Forecast Report 2025-2034

Report ID: FBI 6774| Published Date: Jan-2025| Format: PDF, Excel
Jump to Content
Market Outlook

Market Size and Growth Outlook

Cloud Computing in Energy Market size is projected to rise from USD 1.31 billion in 2024 to USD 3.37 billion by 2034, representing a CAGR above 9.9% for the 2025–2034 forecast period. The industry is estimated to reach USD 1.43 billion in revenue by 2025.

Base Year Value (2024)
USD 1.31 billion
CAGR (2025-2034)
9.9%
Forecast Year Value (2034)
USD 3.37 billion
Historical Data Period
2019-2024
Largest Region
North America
Forecast Period
2025-2034

Get more details on this report

Request Free Sample Report
Snapshot

Cloud Computing in Energy Market Intelligence Snapshot

Regional Market Dynamics

Segment Momentum

Market Expansion Drivers

Leading Market Participants

Forecast Snapshot

Global Market Forecast Snapshot

Market Outlook

Regional and Segment Outlook

Market Dynamics

Market Growth Drivers and Industry Trends

Growth Drivers & Opportunity: One of the major growth drivers in the cloud computing energy market is the increasing demand for data analytics and real-time monitoring. Energy companies are seeking advanced solutions to improve operational efficiency and reduce costs. Cloud computing enables real-time data processing and analytics, allowing organizations to optimize energy use, predict maintenance needs, and enhance decision-making processes. The ability to access and analyze vast amounts of data from various sources is vital for companies aiming to stay competitive in an evolving market. Another significant growth driver is the rise of renewable energy sources and the need for better integration into existing grids. As more energy producers shift towards solar, wind, and other renewable energies, the complexity of energy management increases. Cloud computing technologies offer scalable and flexible platforms that facilitate the integration of renewable sources, enabling efficient energy distribution and grid management. This trend is pushing energy companies to adopt cloud solutions to accommodate fluctuating energy supply and demand dynamics and maintain grid stability. The third growth driver is the acceleration of digital transformation across the energy sector. Traditional energy companies are recognizing the importance of adopting digital technologies to remain competitive. Cloud computing provides the necessary infrastructure for implementing Internet of Things (IoT) applications, machine learning, and artificial intelligence, which are essential for modern energy management. As companies increasingly migrate to cloud-based services, they can enhance their operational capabilities, improve customer engagement, and innovate their service offerings. Industry Restraints: One of the major restraints in the cloud computing energy market is the concern over data security and privacy. Energy companies handle sensitive information and critical infrastructure data, making them attractive targets for cyberattacks. The transition to cloud-based solutions raises concerns regarding the potential for data breaches and unauthorized access. Regulatory compliance also adds an additional layer of complexity, as companies must ensure that their cloud service providers adhere to strict industry standards and regulations. Another significant restraint is the high initial investment and ongoing operational costs associated with cloud migration and management. While cloud computing can reduce long-term operational expenses, the transition process can be costly and resource-intensive. Many energy companies, particularly smaller firms, may struggle with the financial implications of adopting cloud solutions. Additionally, there may be challenges in finding skilled professionals to manage cloud infrastructures, further complicating the adoption process as companies navigate cost constraints and talent shortages.
Custom Research

Unlock insights tailored to your business with our bespoke market research solutions.

Click to get your customized report now.

Request Customization →
Regional Forecast

Regional Demand Dynamics

Cloud Computing in Energy Market
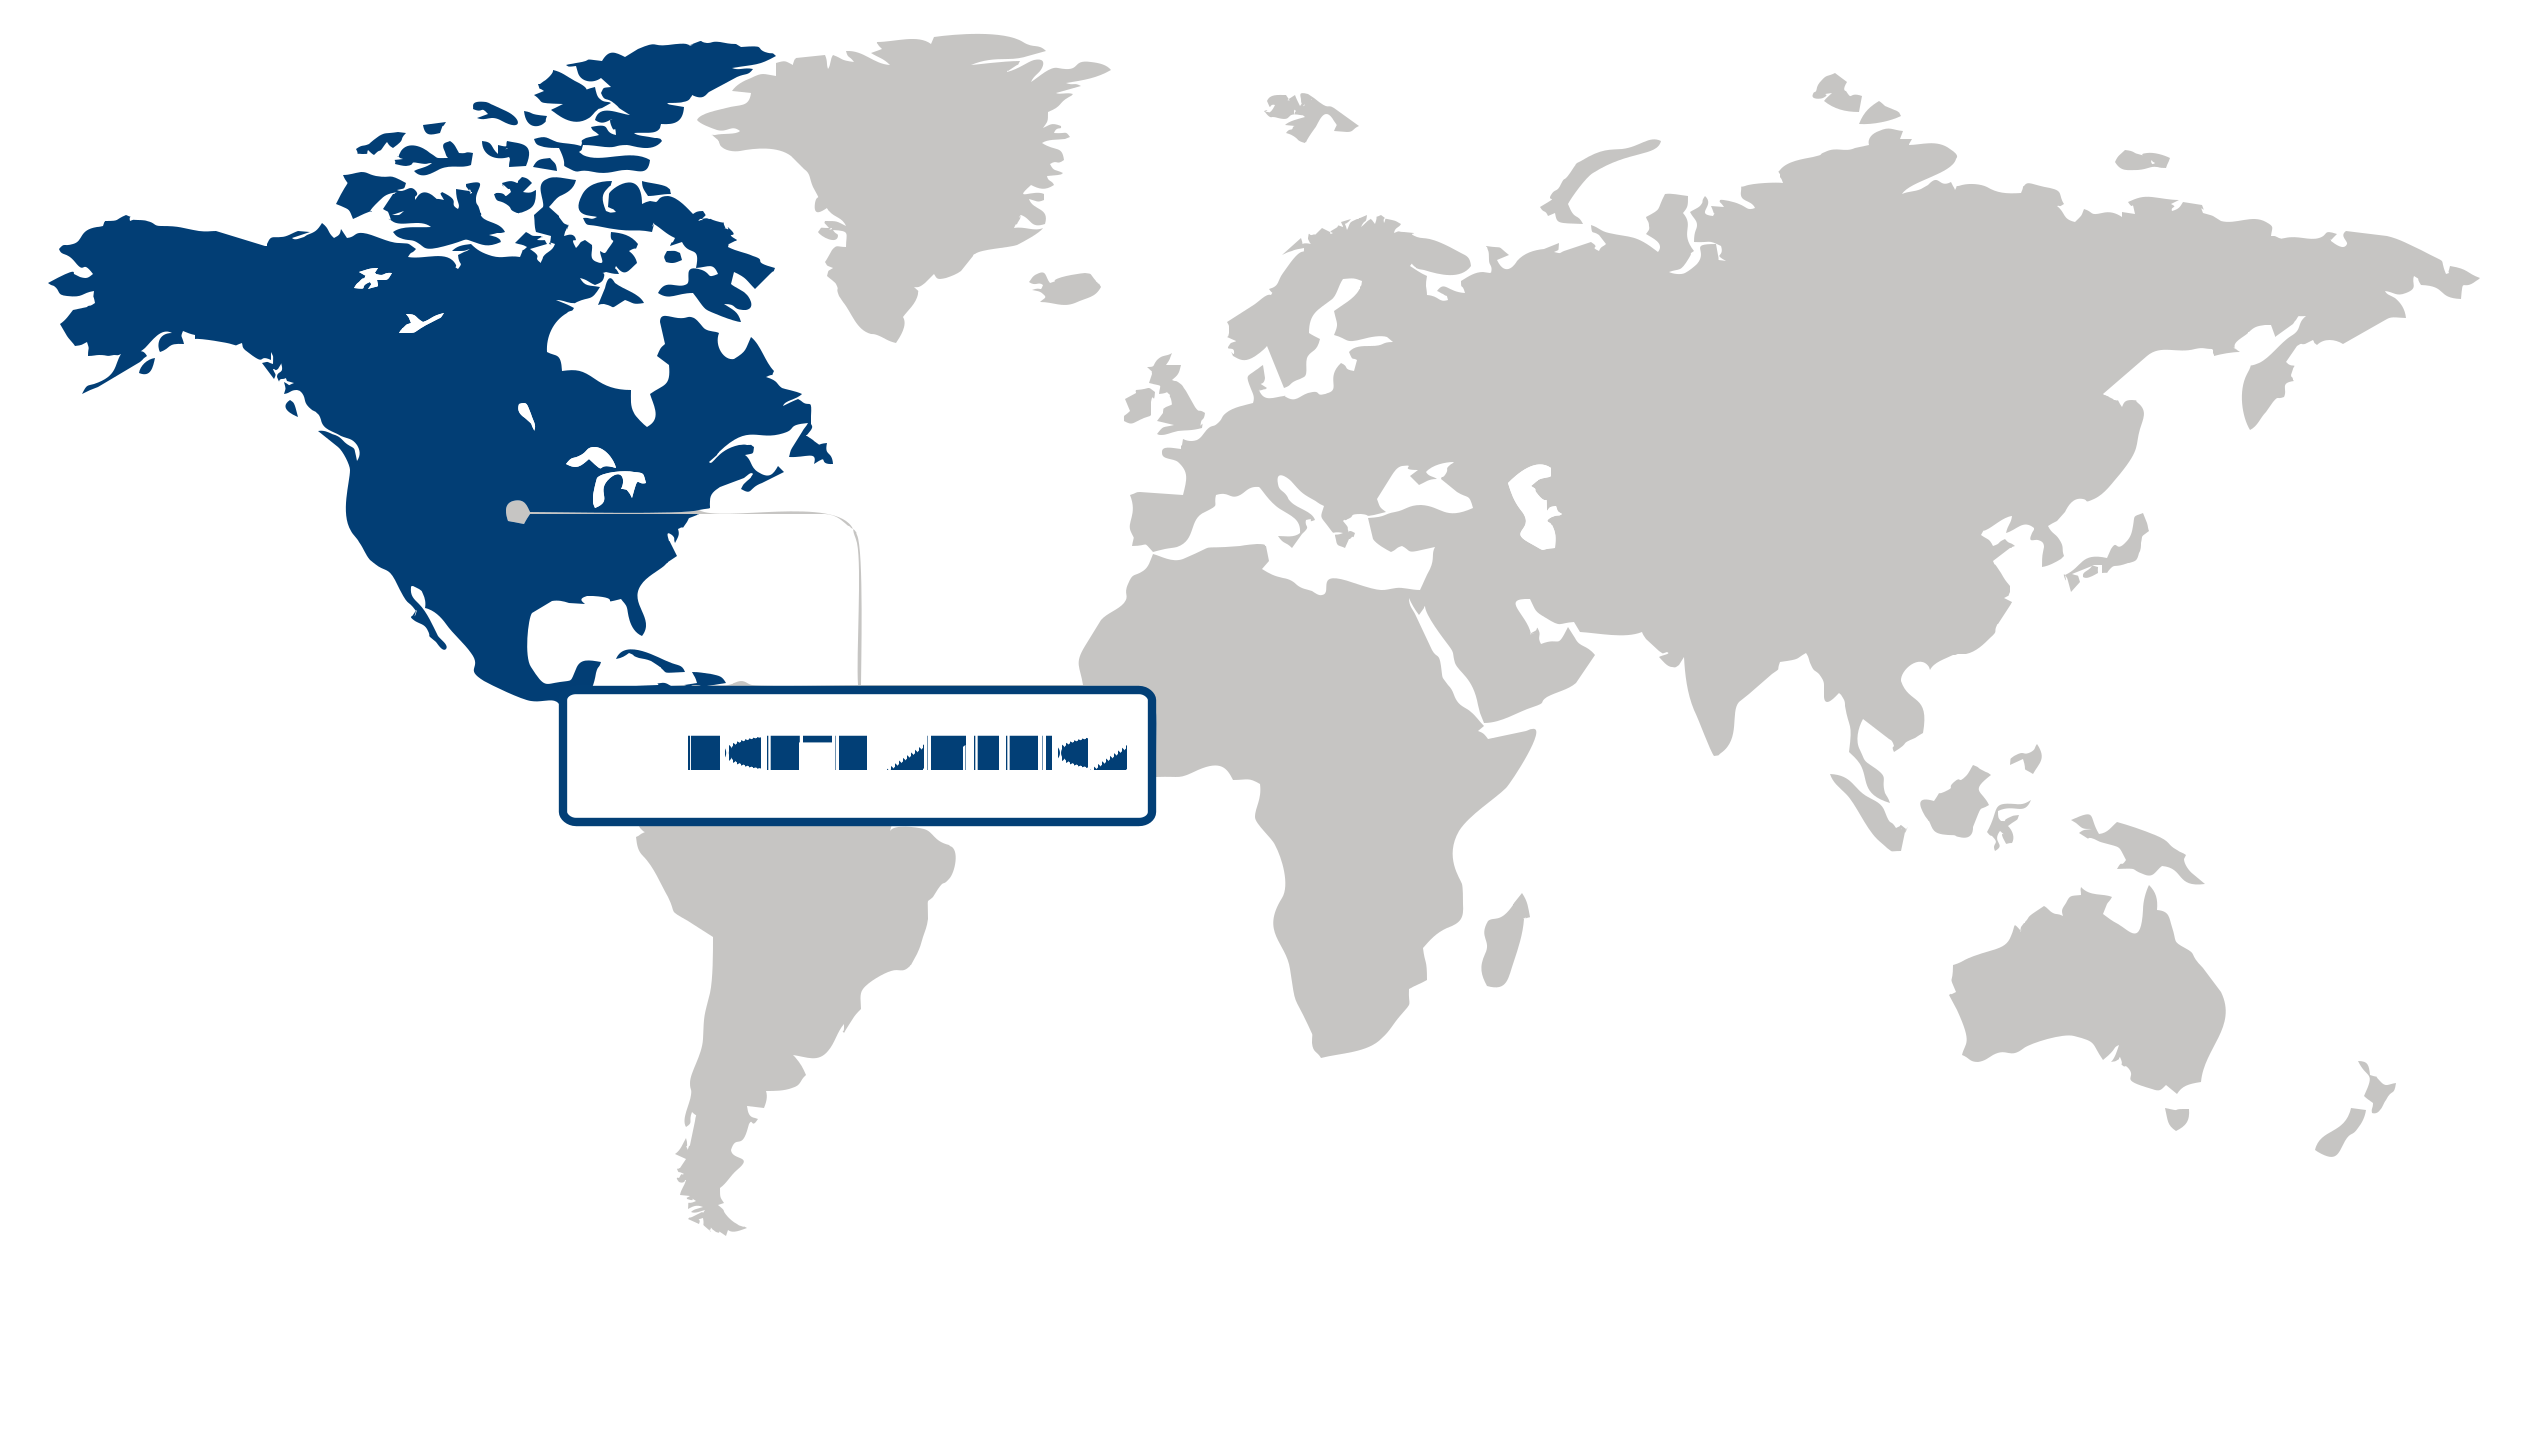
Largest Region
North America
44% Market Share in 2024
North America The cloud computing market in North America is experiencing robust growth, driven by the increasing adoption of advanced technologies such as artificial intelligence, machine learning, and the Internet of Things. The U.S. leads in market share with a dense landscape of major players including AWS, Microsoft Azure, and Google Cloud. Energy companies are leveraging cloud solutions for data analytics, operational efficiency, and enhanced collaboration. Canada is also seeing a rise in cloud adoption, particularly in renewable energy sectors, as regulatory frameworks promote digital transformation. Asia Pacific The Asia Pacific region is witnessing significant advances in cloud computing within the energy market, particularly in China, Japan, and South Korea. China is rapidly expanding its cloud infrastructure with state-owned enterprises transitioning towards cloud-based models, particularly in renewable energy management. Japan is focusing on smart grid technologies and energy-efficient cloud solutions, while South Korea is promoting innovation in energy management through public and private cloud partnerships. Government initiatives in this region aim to integrate cloud solutions for enhanced energy efficiency and sustainability. Europe In Europe, the cloud computing market within the energy sector is characterized by stringent regulations and a strong push towards decarbonization. The United Kingdom is at the forefront, emphasizing cloud solutions for energy optimization and smart grid systems. Germany is leveraging cloud technologies for industrial applications in energy efficiency, while France is focusing on cloud platforms to support renewable energy and storage solutions. Across the region, there is a collective movement toward digital transformation, supported by EU policies aimed at reducing carbon emissions and promoting sustainability through cloud-based technologies.

Go beyond the chart, access full insights & data tables

Request Free Sample Report
Service Analysis The cloud computing segment in the energy market is primarily categorized into three main services: Infrastructure as a Service (IaaS), Platform as a Service (PaaS), and Software as a Service (SaaS). IaaS offers scalable computing resources and storage, which are essential for energy companies looking to manage vast amounts of data generated from operations, such as monitoring energy consumption and predictive maintenance. PaaS enables developers to build, test, and deploy applications in a flexible environment, allowing energy firms to innovate rapidly. Finally, SaaS provides ready-to-use software solutions that enhance operational efficiency and digital transformation in energy management. As cloud adoption grows, the distinction among these services will increasingly drive competitive advantage, with many energy companies opting for a hybrid approach, utilizing IaaS for infrastructure, PaaS for application development, and SaaS for operational tools. Platform Analysis In the realm of platforms, key players such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud Platform (GCP) dominate the cloud computing landscape within the energy sector. AWS leads the market with an extensive range of services that cater specifically to energy companies, including advanced data analytics and machine learning capabilities for smarter energy management. Microsoft Azure follows closely, emphasizing enterprise-level scalability and seamless integration with existing Microsoft tools, appealing to energy firms seeking robust solutions. GCP stands out for its data analytics prowess and artificial intelligence capabilities, making it popular for companies focusing on predictive analytics and renewable energy projects. Other platforms are also emerging, but dominant players continue to shape the market through innovative offerings and strategic partnerships tailored to the unique needs of the energy industry. Infrastructure Analysis The infrastructure segment critical to cloud computing in the energy market comprises servers, storage, and networking equipment. Servers are the backbone of cloud services, providing the computational power necessary for processing large datasets generated by energy operations. Energy companies are increasingly transitioning to cloud-based server solutions that allow for more flexibility and scalability. Storage plays a vital role as well, with energy firms requiring robust, secure solutions to manage sensitive data, including customer information and operational analytics. Networking equipment is equally essential, facilitating seamless data transfer and communication between cloud platforms and on-site operational technology. As the energy sector embraces digital transformation, investments in specialized infrastructure will likely expand, allowing for more efficient energy management and improved operational resilience.
Segment Sub-Segment Largest Segment Fastest Growing
Competitive Landscape

Competitive Landscape and Market Positioning

The competitive landscape in the Cloud Computing in Energy Market is marked by rapid technological advancements and increasing demand for digital transformation within the energy sector. Major players are leveraging cloud solutions to enhance operational efficiency, optimize resource management, and improve data analytics. Additionally, partnerships between cloud service providers and energy companies are becoming more prevalent, enabling the development of innovative solutions that address the specific needs of the energy industry, such as renewable energy integration and smart grid management. As the market evolves, companies are focusing on sustainability, scalability, and security to gain a competitive edge while addressing regulatory requirements and customer expectations. Top Market Players 1. Microsoft Azure 2. Amazon Web Services 3. Google Cloud Platform 4. IBM Cloud 5. SAP 6. Oracle 7. Siemens 8. Schneider Electric 9. GE Digital 10. Accenture
Company Market Share Company Revenue Revenue CAGR (%) Product Portfolio Geographic Presence Innovation / R&D Focus Strategic Developments
No companies available.
🔒 This section is available as a standalone purchase. Buy only the data you need. Inquire Before Buying
Report Customization

Customize Your Report

Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.

1 Custom Segments 2 Custom TOC 3 Related Reports

Cloud Computing in Energy Market — Custom Segments

Segment Sub-Segment
No segment data available.

Cloud Computing in Energy Market — Custom TOC

Custom Chapter Chapter Details
No custom TOC data available.

Need a different cut of the data?

Request Custom Research
FAQ

Frequently Asked Questions

Testimonials

Our Clients

"The team demonstrated a great understanding of our business needs, and the reports were tailored to address our specific concerns and objectives."

Delivery Manager
Infosys

"The report was up-to-date with the latest industry trends and technological advancements. The detailed competitive landscape analysis was quite helpful."

Network Engineer
Zebra Technologies

"The data presented in the report was accurate and well-researched. I also found the market dynamics section particularly useful."

Senior Sales Manager
Arlo Technologies
THE RESEARCH BEHIND THIS REPORT

Our Research Team & Methodology

Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.

THIS REPORT'S RESEARCH VERTICAL
Smart Technologies
Research Team Overview

This report was prepared by the Smart Technologies Research Team at Fundamental Business Insights, a dedicated research group specializing in emerging digital technologies and intelligent connected systems. Our analysts continuously monitor advancements in artificial intelligence, Internet of Things (IoT), cloud computing, edge computing, cybersecurity, automation, digital transformation strategies, and evolving enterprise adoption trends to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with technology providers, software vendors, system integrators, enterprise users, and industry experts, along with company annual reports, investor presentations, regulatory publications, technology standards, industry associations, technical white papers, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.

Prepared by the Smart Technologies Research Team
10+Industry Verticals
100+Countries Analyzed
5-7Days Standard
Delivery
12k+Research Reports
Published
On-DemandCustomized Research
Available
6Months Analyst
Support
PDF + XLSReport Deliverables
Trust & Compliance
D&B D-U-N-S
GDPR & CCPA Compliant
ISO 9001 Certified (ISO 9001:2015)
SSL Encryption
Secure Payments
Confidential Handling
Research Intelligence
Primary Research Network
Secondary Sources
Executive Leadership
Product & Technology Experts
Manufacturing & Operations Leaders
Procurement & Supply Chain Professionals
Sales & Commercial Executives
Channel Partners & Distribution Networks
Enterprise Buyers & End Users
Industry Consultants & Regulatory Experts
Research Workflow & Quality Assurance
01
Data Collection
Verified information gathered through primary and secondary research.
02
Data Triangulation
Cross-validation using multiple independent data sources.
03
Forecast Modelling
Market estimates developed using historical trends and analytical models.
04
Analyst Validation
Findings reviewed by domain experts for accuracy and consistency.
05
Editorial & Quality Review
Final editorial, quality, and compliance checks before publication.
06
Final Publication
Released after successful completion of the internal review process.
Report Coverage
Market Assessment
  • Market Size & Forecast
  • Market Segmentation
  • Regional Analysis
  • Growth Drivers & Challenges
  • Market Dynamics
🏢 Competitive Intelligence
  • Competitive Landscape
  • Company Profiles
  • Competitive Benchmarking
  • Mergers & Acquisitions
  • Market Share Analysis or Key Company Strategies
🔍 Strategic Analysis
  • Value Chain Analysis
  • Porter's Five Forces
  • PESTLE Analysis
  • Pricing Trends
  • Supply-Demand Analysis
🚀 Future Outlook
  • Technology Landscape
  • Regulatory Landscape
  • Investment & Funding Landscape
  • Emerging Opportunities
  • Future Market Outlook
Have a question about this report or need a custom scope?
Request Customization
License

Select License Type

Single User
US$ 4,250
Buy Now
Corporate User
US$ 6,150
Buy Now

Want this data scoped to your exact question?

Tell us the segments, regions, or competitors you need answered — an analyst will confirm scope before any custom work starts.

Talk to an Analyst →