Personal Computers Market Size & Growth Forecast 2027–2036, By Segments (Distribution Channel, End-use, Type), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Personal Computers Market size was more than USD 179.9 billion in 2026 and is set to grow at a 7.6% CAGR between 2027 and 2036, attaining USD 374.24 billion by 2036. The industry revenue for 2027 is estimated at USD 191.41 billion.
Get more details on this report
Request Free Sample ReportPersonal Computers Market Intelligence Snapshot
Regional Market Dynamics
- Asia Pacific leads the personal computers market due to its deep electronics manufacturing base, extensive supply chains, and broad consumer and commercial demand, supporting strong product availability across price segments.
- Asia Pacific is projected to grow at a 9.04% CAGR, driven by replacement cycles, expanding digital access, and steady procurement across education, business, and household applications.
Segment Momentum
- The Commercial segment held a 56.7% share in 2026, supported by recurring enterprise demand for reliable desktops and laptops, standardized deployments, and ongoing device replacement across organizational environments.
- Offline Retail is expanding fastest as buyers increasingly prefer hands-on evaluation, live demonstrations, immediate assistance, and same-day product availability before purchasing higher-value personal computers.
Market Expansion Drivers
- Expanding remote work and online education accelerating demand for portable high-performance laptops.
- Rising gaming and multimedia content creation driving premium PC and peripheral upgrades.
- Increasing enterprise device refresh cycles supporting commercial PC procurement and infrastructure modernization.
Leading Market Participants
- Prominent companies in the personal computers market include Apple Inc. (United States), Lenovo Group Limited (China), Dell Technologies Inc. (United States), HP Inc. (United States), Acer Inc. (Taiwan), ASUSTeK Computer Inc. (Taiwan), Micro-Star International Co., Ltd. (Taiwan), Samsung Electronics Co., Ltd. (South Korea), Microsoft Corporation (United States), LG Electronics Inc. (South Korea).
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 179.9 billion
- 2027 Estimated Market Size: USD 191.41 billion.
- Projected Market Size: USD 374.24 billion by 2036
- Growth Forecast: 7.6% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Asia Pacific
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Online Retail (Distribution Channel) | Commercial (End-use) | Laptops (Type)
- Emerging Opportunity Segment: Offline Retail (Distribution Channel) | Consumer (End-use) | Laptops (Type)
Market Growth Drivers and Industry Trends
Expanding remote work and online education accelerating demand for portable high-performance laptops
Remote work and online education are contributing to the personal computers market as users require reliable devices capable of supporting video conferencing, productivity applications, virtual classrooms, collaboration platforms, and multitasking from different locations. Laptops with improved processing capabilities, battery efficiency, connectivity, and portability are particularly suited to these usage patterns because they allow users to move between home, educational institutions, offices, and other environments. The need to combine professional, academic, and personal activities on a single device is also increasing demand for versatile computing systems.
Rising gaming and multimedia content creation driving premium PC and peripheral upgrades
Demand for more demanding gaming and content creation experiences will propel the personal computers market as users seek higher processing performance, advanced graphics capabilities, faster storage, and improved display quality. Modern games, video editing applications, animation workflows, and other multimedia tasks place greater demands on system hardware, encouraging users to upgrade from basic configurations to performance-oriented PCs. This trend also supports spending on complementary peripherals such as high-resolution monitors, specialized input devices, audio equipment, and other accessories that enhance gaming and creative workflows.
Increasing enterprise device refresh cycles supporting commercial PC procurement and infrastructure modernization
Enterprise technology refresh programs are supporting the personal computers market as organizations replace aging devices to maintain employee productivity, security, and compatibility with newer software environments. Businesses increasingly evaluate computing equipment based on processing performance, manageability, security features, connectivity, and support for hybrid work arrangements. Replacing outdated systems can also help organizations standardize their hardware fleets and improve IT administration, while modernization initiatives encourage procurement of devices that can accommodate evolving workplace applications and digital collaboration requirements.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Expanding remote work and online education accelerating demand for portable high-performance laptops | 2.00% | Moderate | North America, Asia Pacific | High | Near Term |
| Rising gaming and multimedia content creation driving premium PC and peripheral upgrades | 1.70% | Low | North America, Europe, Asia Pacific | High | Mid Term |
| Increasing enterprise device refresh cycles supporting commercial PC procurement and infrastructure modernization | 1.40% | Moderate | North America, Europe | Emerging | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
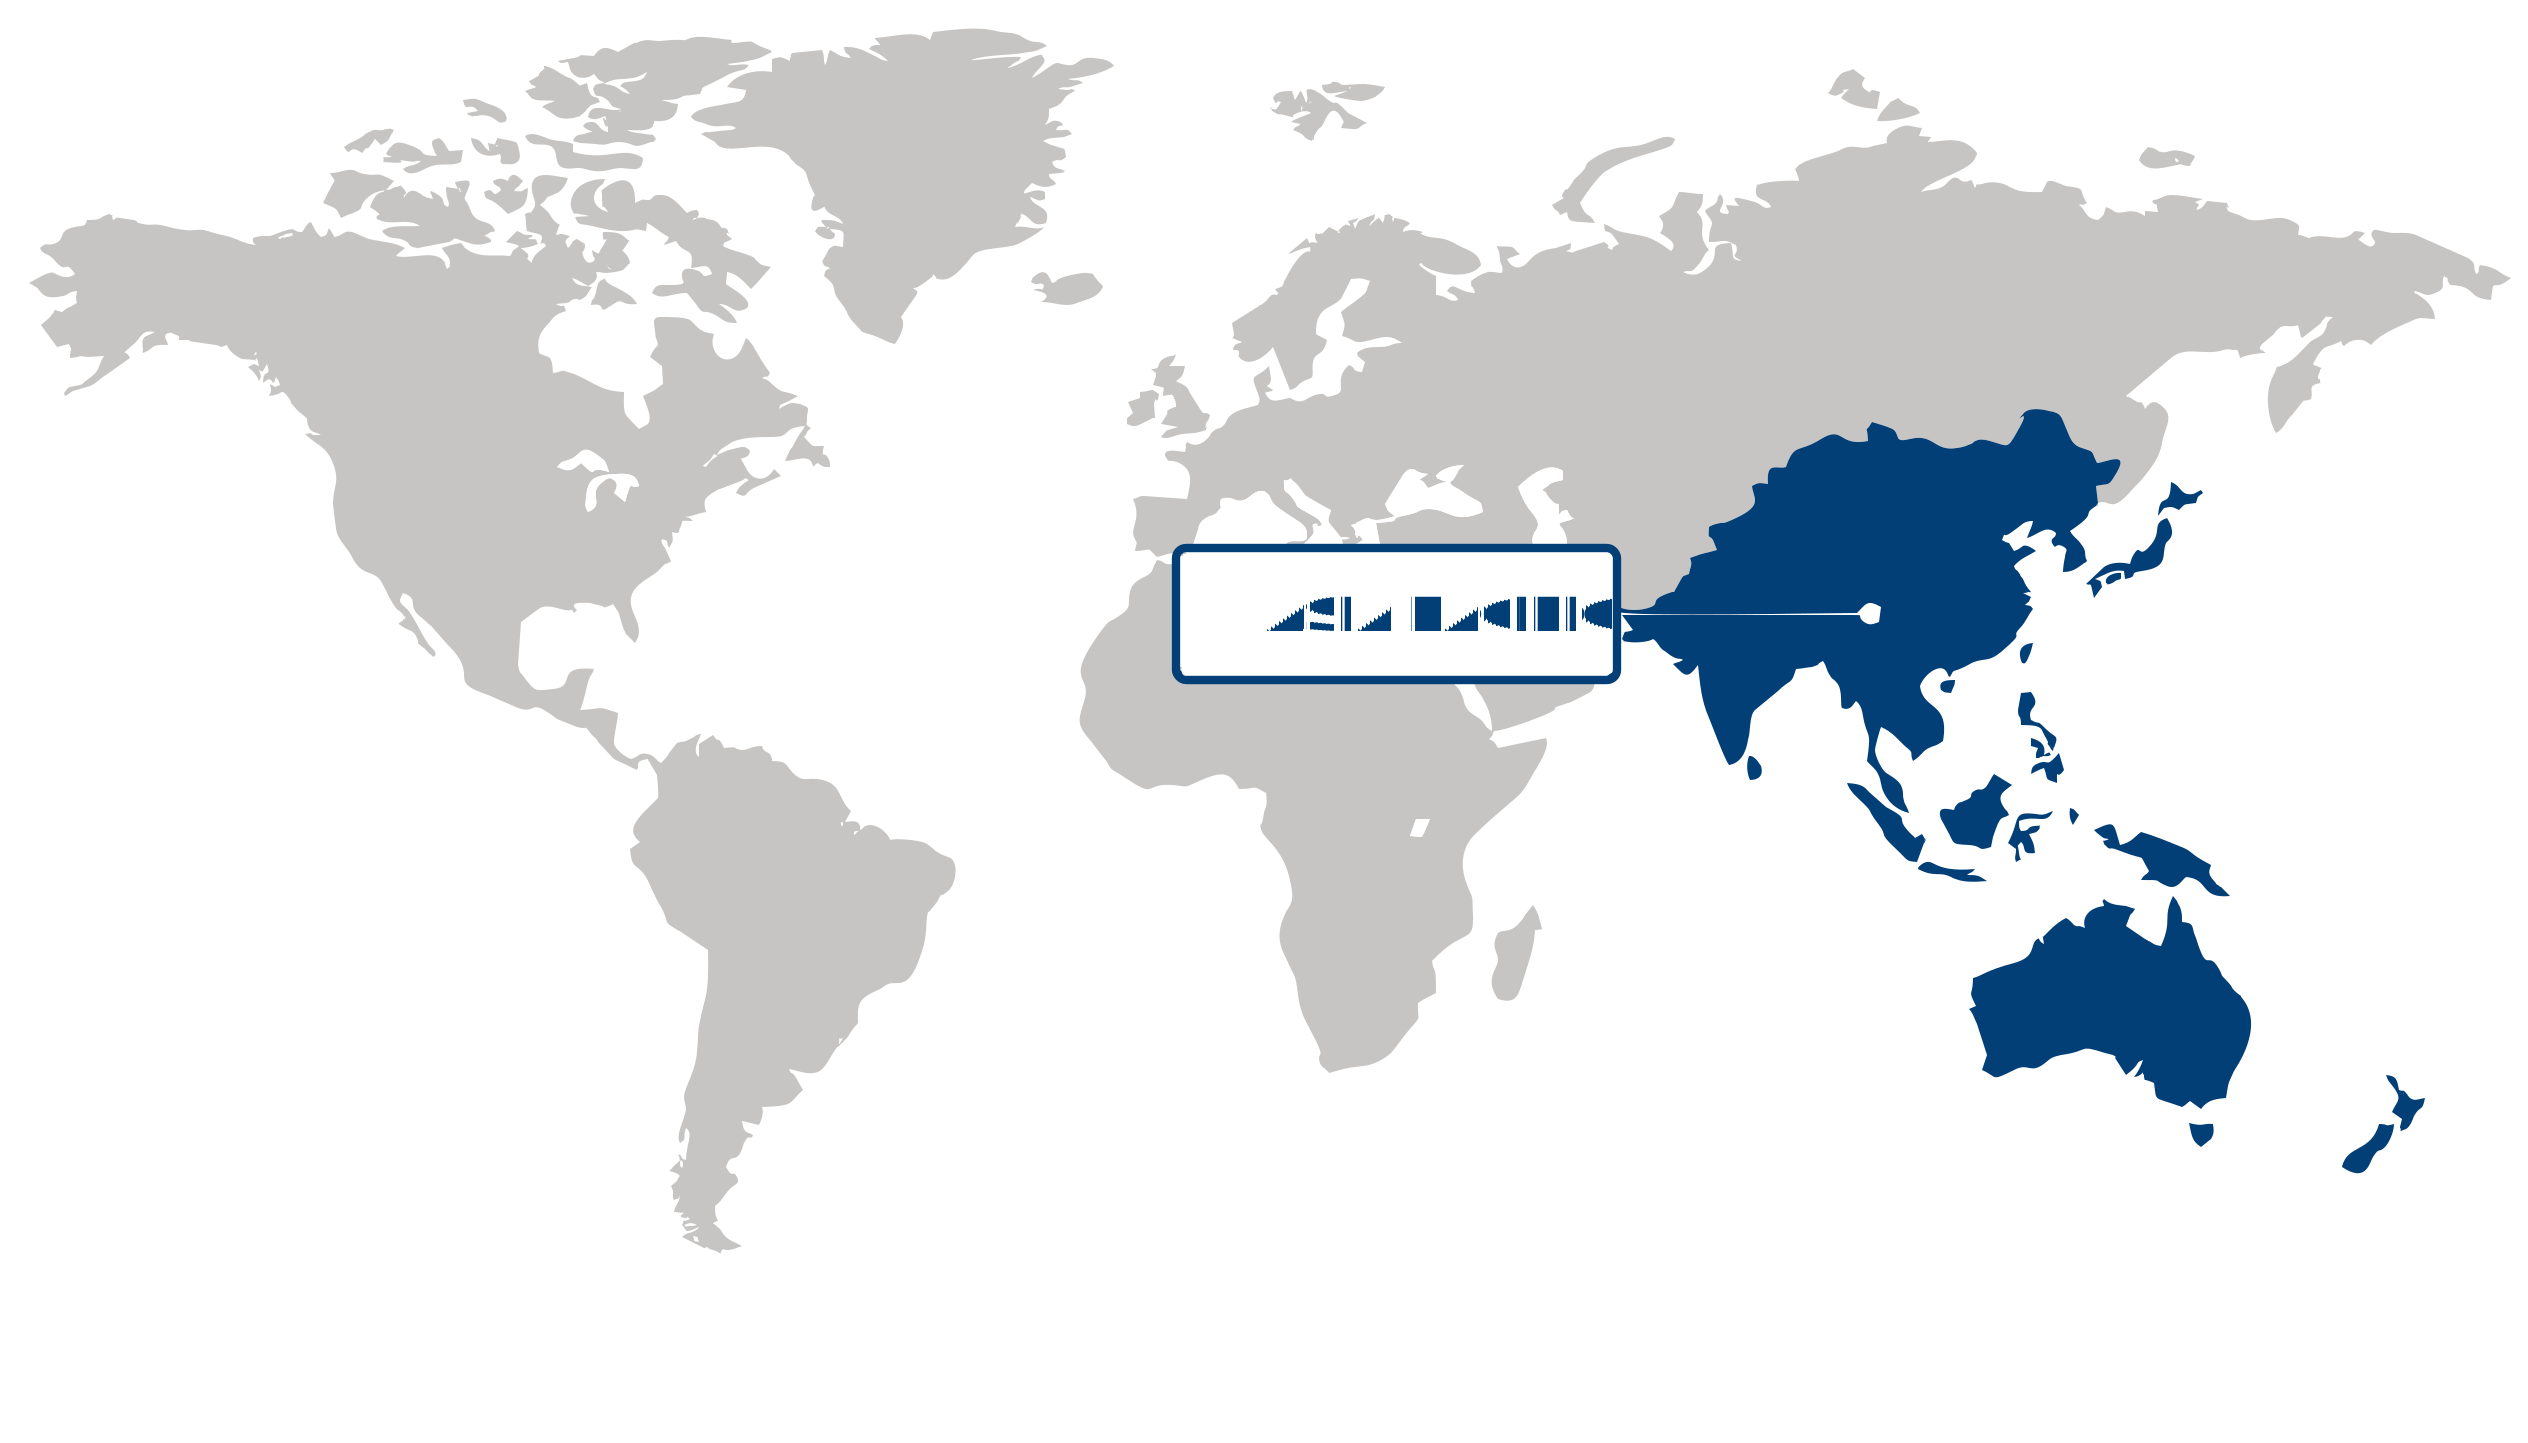
Asia Pacific (Largest & Fastest-Growing Region)
Asia Pacific held the largest share of the personal computers market in 2026 while also representing the fastest-growing region, supported by its extensive electronics manufacturing ecosystem, expanding digital workforce, and broadening adoption of computing devices across consumer and business segments. Rising demand for remote productivity, education, gaming, and content creation is sustaining purchases, while improvements in device performance, portability, and connectivity are encouraging replacement and first-time adoption. The region’s expanding technology infrastructure and increasing digitalization of enterprises and educational institutions further strengthen demand, with local manufacturing capabilities helping support product availability and market development.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
Germany 🇩🇪
Industrial Productivity ComputingGermany prioritizes personal computers that support engineering, manufacturing, and business productivity applications. Buyers increasingly value durable hardware, energy-efficient designs, and secure enterprise management capabilities for long-term operational use.
France 🇫🇷
Workplace Digital ModernizationFrance continues investing in personal computers to support digital workplaces, education, and public sector modernization. Purchasing decisions increasingly prioritize sustainable hardware, reliable security features, and efficient fleet management for organizational deployments.
Italy 🇮🇹
SME Technology AdoptionItaly's personal computers market is driven by small and medium-sized businesses upgrading workplace technology alongside steady consumer demand. Suppliers emphasize affordable performance, dependable after-sales support, and versatile product portfolios for diverse user needs.
Japan 🇯🇵
Compact Performance DemandJapan's personal computers market favors lightweight, high-performance devices suited for business users, education, and professional mobility. Manufacturers continue refining compact designs while integrating advanced processing capabilities and enhanced battery efficiency.
South Korea 🇰🇷
Connected Digital EcosystemSouth Korea's personal computers market benefits from strong digital adoption and seamless integration with connected consumer and business devices. Vendors focus on premium notebooks, gaming systems, and AI-enhanced features that complement evolving computing preferences.
United States 🇺🇸
Enterprise Refresh CycleThe U.S. personal computers market is supported by enterprise device replacement, hybrid work requirements, and demand for AI-enabled computing. Vendors emphasize performance, security, and device lifecycle services as organizations modernize workplace technology infrastructure.
Personal Computers Market Share (%), by Distribution Channel, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportDistribution Channel Segment Analysis: Online Retail (Largest Segment) vs Offline Retail (Fastest-Growing Segment)
Online retail dominated the personal computers market with a 55.65% share in 2026, supported by the convenience of broad product availability, simplified comparison of specifications, and flexible purchasing options. Digital channels allow consumers and businesses to evaluate different configurations, features, and price points before making purchasing decisions, while direct access to product information supports more informed technology selection. The continued integration of digital commerce into electronics purchasing is reinforcing the importance of online distribution.
Offline retail is the fastest-growing segment as buyers continue to value physical product evaluation, personalized assistance, and immediate access to devices. In-store purchasing enables customers to assess display quality, keyboard and build characteristics, and overall usability before committing to a computer, which remains relevant for higher-value technology purchases. Retail outlets also provide opportunities for demonstrations, installation assistance, and after-sales support, strengthening their role alongside digital channels.
End-use Segment Analysis: Commercial (Largest Segment) vs Consumer (Fastest-Growing Segment)
The commercial segment led the personal computers market, holding a 56.7% share in 2026. Demand is sustained by the widespread use of computers across business operations, including office productivity, communication, data management, content creation, and specialized professional workloads. Organizations also require devices that can support increasingly digitalized workplace environments, making reliable computing infrastructure an important part of business operations and workforce productivity.
Consumer represents the fastest-growing segment, driven by increasing reliance on personal computing for education, remote work, entertainment, content creation, and everyday digital activities. Consumers are also seeking devices that combine portability, performance, and connectivity across a wider range of use cases. The expanding role of computers in home-based productivity and digital lifestyles is supporting continued demand within the consumer segment.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Distribution Channel | Online Retail, Offline Retail | Online Retail | Offline Retail |
| End-use | Consumer, Commercial | Commercial | Consumer |
| Type | Desktops, Laptops, Tablets, Others | Laptops | Laptops |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Prominent players in the personal computers market:
1. Apple Inc. (United States)
2. Lenovo Group Limited (China)
3. Dell Technologies Inc. (United States)
4. HP Inc. (United States)
5. Acer Inc. (Taiwan)
6. ASUSTeK Computer Inc. (Taiwan)
7. Micro-Star International Co. Ltd. (Taiwan)
8. Samsung Electronics Co. Ltd. (South Korea)
9. Microsoft Corporation (United States)
10. LG Electronics Inc. (South Korea)
The personal computers market is undergoing transformation driven by demand for high-performance and versatile computing systems. Within the personal computers market, advancements in processing power and AI integration are enhancing user experience. New device configurations are being introduced to support hybrid work and gaming needs. Differentiation is increasingly based on performance optimization and ecosystem integration.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Apple Inc. (United States) | |||||||
| Lenovo Group Limited (China) | |||||||
| Dell Technologies Inc. (United States) | |||||||
| HP Inc. (United States) | |||||||
| Acer Inc. (Taiwan) | |||||||
| ASUSTeK Computer Inc. (Taiwan) | |||||||
| Micro-Star International Co. Ltd. (Taiwan) | |||||||
| Samsung Electronics Co. Ltd. (South Korea) | |||||||
| Microsoft Corporation (United States) | |||||||
| LG Electronics Inc. (South Korea). |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| Apple | May-26 | The company entered a talent and intellectual property agreement with Animato, a startup specializing in virtual avatar software. By acquiring key talent and licensing intellectual property, Apple aims to bolster its digital user experiences and avatar-based software capabilities for computing platforms and high-end mixed reality devices. |
| Sep-25 | Google announced "Aluminium OS," an Android-based operating system for personal computers. The platform integrates Gemini AI and is designed to merge Android's mobile ecosystem with desktop-grade productivity, marking a strategic expansion of Google's presence in the PC software segment and its transition away from ChromeOS. | |
| T-Mobile | Sep-25 | T-Mobile partnered with local municipal authorities and Dell to distribute 350,000 Chromebooks to K-12 students. This initiative significantly expands the reach of personal computing devices in the education sector while supporting broader corporate social responsibility and digital inclusion strategies. |
| Huawei | May-25 | Huawei launched its proprietary HarmonyOS for personal computers, featuring a microkernel design and cross-platform "Super Device" capabilities. This strategic development significantly reduces reliance on external operating systems and establishes a unified software ecosystem across the company’s smartphone, tablet, and PC hardware portfolios. |
| Dell Technologies | Jan-25 | Dell launched a specialized portfolio of AI-optimized personal computers. This hardware initiative is designed to accelerate enterprise-level AI deployment and address the specialized performance and power requirements of next-generation workplace computing in a market increasingly defined by AI integration. |
| NVIDIA | Nov-24 | NVIDIA announced its entry into the PC processor market through the development of dedicated CPUs. This strategic move represents a significant expansion of its hardware footprint and increases competitive pressure within the processor segment, historically dominated by established incumbents. |
| Apple | Oct-24 | Apple introduced upgraded MacBook Pro models featuring M4 Pro and M4 Max silicon. This refresh strengthens the company’s competitive positioning in the high-performance computing segment by delivering incremental gains in processing power and thermal efficiency, essential for professional workflows. |
| Intel | Jun-24 | Intel deepened strategic partnerships with Samsung and LG to advance the adoption of AI-enabled PCs. By collaborating on hardware integration and artificial intelligence capabilities, Intel aims to solidify its position as the foundational processor provider in the emerging "AI PC" device category. |
| Microsoft | May-24 | Microsoft unveiled its next-generation AI-powered PC platform, integrating native artificial intelligence capabilities into the mainstream computing experience. This development signals a major shift in the company’s strategy to incorporate large language model processing directly into the desktop user experience to drive device refreshes and productivity. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Personal Computers Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| User Performance Segment | Entry-Level, Mainstream, Performance, Professional/Workstation |
| Operating System | Windows, macOS, ChromeOS, Linux, Other Operating Systems |
| Connectivity Capability | Wi-Fi Only, Wi-Fi + Bluetooth, Cellular-Enabled, Advanced Enterprise Connectivity |
Personal Computers Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| AI PC Adoption Opportunities |
|
| Enterprise Computing Transformation |
|
| PC Replacement Cycle Assessment |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
What is the market valuation of personal computers?
What is the projected value of the personal computers industry by 2036?
How is hybrid work and digital education reshaping demand for portable high-performance PCs?
How are gaming and creator workloads influencing upgrade cycles and PC purchasing behavior?
Why is the Commercial segment the largest end-use category in the personal computers market?
Why is Offline Retail the fastest-growing distribution channel in the personal computers market?
Why does Asia Pacific lead the personal computers market?
What is driving the growth of the personal computers market in Asia Pacific?
Which companies dominate the personal computers landscape?
Our Clients
"Working with FBI has been a good experience. The market report provided a holistic view, covering everything from emerging trends to potential risks."
Semtech Corporation
"The experience was highly positive. The team showcased remarkable flexibility in adapting to our specific needs and delivered report that perfectly aligned with all our requirements."
TSMC
"What really stood out to me was how clearly and promptly the Fundamental Business Insights team communicated throughout. It made the collaboration feel effortless."
NXP Semiconductors
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Electronics & Semiconductors Research Team at Fundamental Business Insights, a dedicated research group specializing in the global electronics and semiconductor ecosystem. Our analysts continuously monitor technology innovations, manufacturing trends, competitive developments, supply chain dynamics, regulatory changes, and end-user demand to deliver timely market intelligence. The research is developed using a structured methodology that combines primary industry interactions, company financial disclosures, government publications, trade associations, technical literature, patent analysis, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook