EV Platform Market Size & Growth Forecast 2027–2036, By Segments (Vehicle, Sales Channel, Propulsion, Platform, Component), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
EV Platform Market size was assessed at USD 20.17 Billion in 2026 and is poised to grow at 21.52% CAGR between 2027 and 2036, crossing USD 141.64 Billion by 2036. The industry revenue for 2027 is calculated at USD 24 Billion.
Get more details on this report
Request Free Sample ReportEV Platform Market Intelligence Snapshot
Regional Market Dynamics
- Asia Pacific held 37.8% of the market in 2026, supported by expanding electric mobility, strong automotive manufacturing capabilities, and substantial investment in vehicle electrification.
- Continued charging infrastructure expansion, supportive electrification policies, and advances in battery and vehicle technologies are accelerating demand for scalable EV platforms across the region.
Segment Momentum
- Passenger cars held a 61.48% market share in 2026, driven by strong consumer demand, expanding electric vehicle model availability, supportive policies, improving charging infrastructure, and sustained investments in dedicated EV platforms.
- Commercial vehicles are expanding fastest as fleet operators adopt electrified buses, delivery vans, and heavy-duty vehicles to reduce operating costs, meet emissions regulations, and support growing logistics and public transportation electrification.
Market Expansion Drivers
- Surge in global electric vehicle adoption accelerating modular EV platform deployment
- OEM transition toward scalable modular architectures reducing development and production costs
- Expansion of EV charging infrastructure supporting ecosystem-wide platform standardization
Leading Market Participants
- Prominent players in the EV platform market include Tesla, Inc. (United States), BYD Company Limited (China), Toyota Motor Corporation (Japan), Volkswagen AG (Germany), General Motors Company (United States), Ford Motor Company (United States), Hyundai Motor Company (South Korea), Stellantis N.V. (Netherlands), Rivian Automotive, Inc. (United States), NIO Inc. (China)
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 20.17 Billion
- 2027 Estimated Market Size: USD 24 Billion
- Projected Market Size: USD 141.64 Billion by 2036
- Growth Forecast: 21.52% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Asia Pacific
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Passenger Cars (Vehicle) | OEM (Sales Channel) | Battery Electric Vehicles (BEV) (Propulsion) | P3 (Platform) | Battery (Component)
- Emerging Opportunity Segment: Commercial Vehicles (Vehicle) | OEM (Sales Channel) | Battery Electric Vehicles (BEV) (Propulsion) | P3 (Platform) | Battery (Component)
Market Growth Drivers and Industry Trends
Surge in global electric vehicle adoption accelerating modular EV platform deployment
The rapid expansion of electric vehicle adoption is encouraging manufacturers to accelerate the deployment of modular vehicle architectures capable of supporting multiple models and powertrain configurations. This shift will boost the EV platform market demand as automakers seek flexible foundations that simplify production while responding quickly to changing consumer preferences. Modular platforms also improve manufacturing efficiency by enabling greater component sharing, streamlined assembly processes, and faster introduction of new electric vehicle models across different market segments.
OEM transition toward scalable modular architectures reducing development and production costs
As original equipment manufacturers increasingly prioritize platform standardization, scalable vehicle architectures are becoming central to product development strategies. The EV platform market growth is driven by the industry's focus on reducing engineering complexity, shortening design timelines, and optimizing manufacturing resources across diverse vehicle portfolios. Shared architectures allow manufacturers to distribute development costs across multiple vehicle programs while improving procurement efficiency and supporting faster adaptation to evolving regulatory and market requirements.
Expansion of EV charging infrastructure supporting ecosystem-wide platform standardization
Wider availability of charging infrastructure is creating a more mature electric mobility ecosystem that encourages greater alignment in vehicle design and technology integration. This development will propel the EV platform market growth by supporting standardized electrical architectures, battery compatibility, and software integration across different vehicle categories. Improved charging accessibility also encourages manufacturers to adopt common platform strategies that simplify interoperability while enhancing production planning and long-term product scalability.
#
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Surge in global electric vehicle adoption accelerating modular EV platform deployment | 2.4% | High | Asia Pacific, Europe | High | Near Term |
| OEM transition toward scalable modular architectures reducing development and production costs | 2.2% | High | North America, Europe | High | Near Term |
| Expansion of EV charging infrastructure supporting ecosystem-wide platform standardization | 2.1% | High | Asia Pacific, North America | High | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
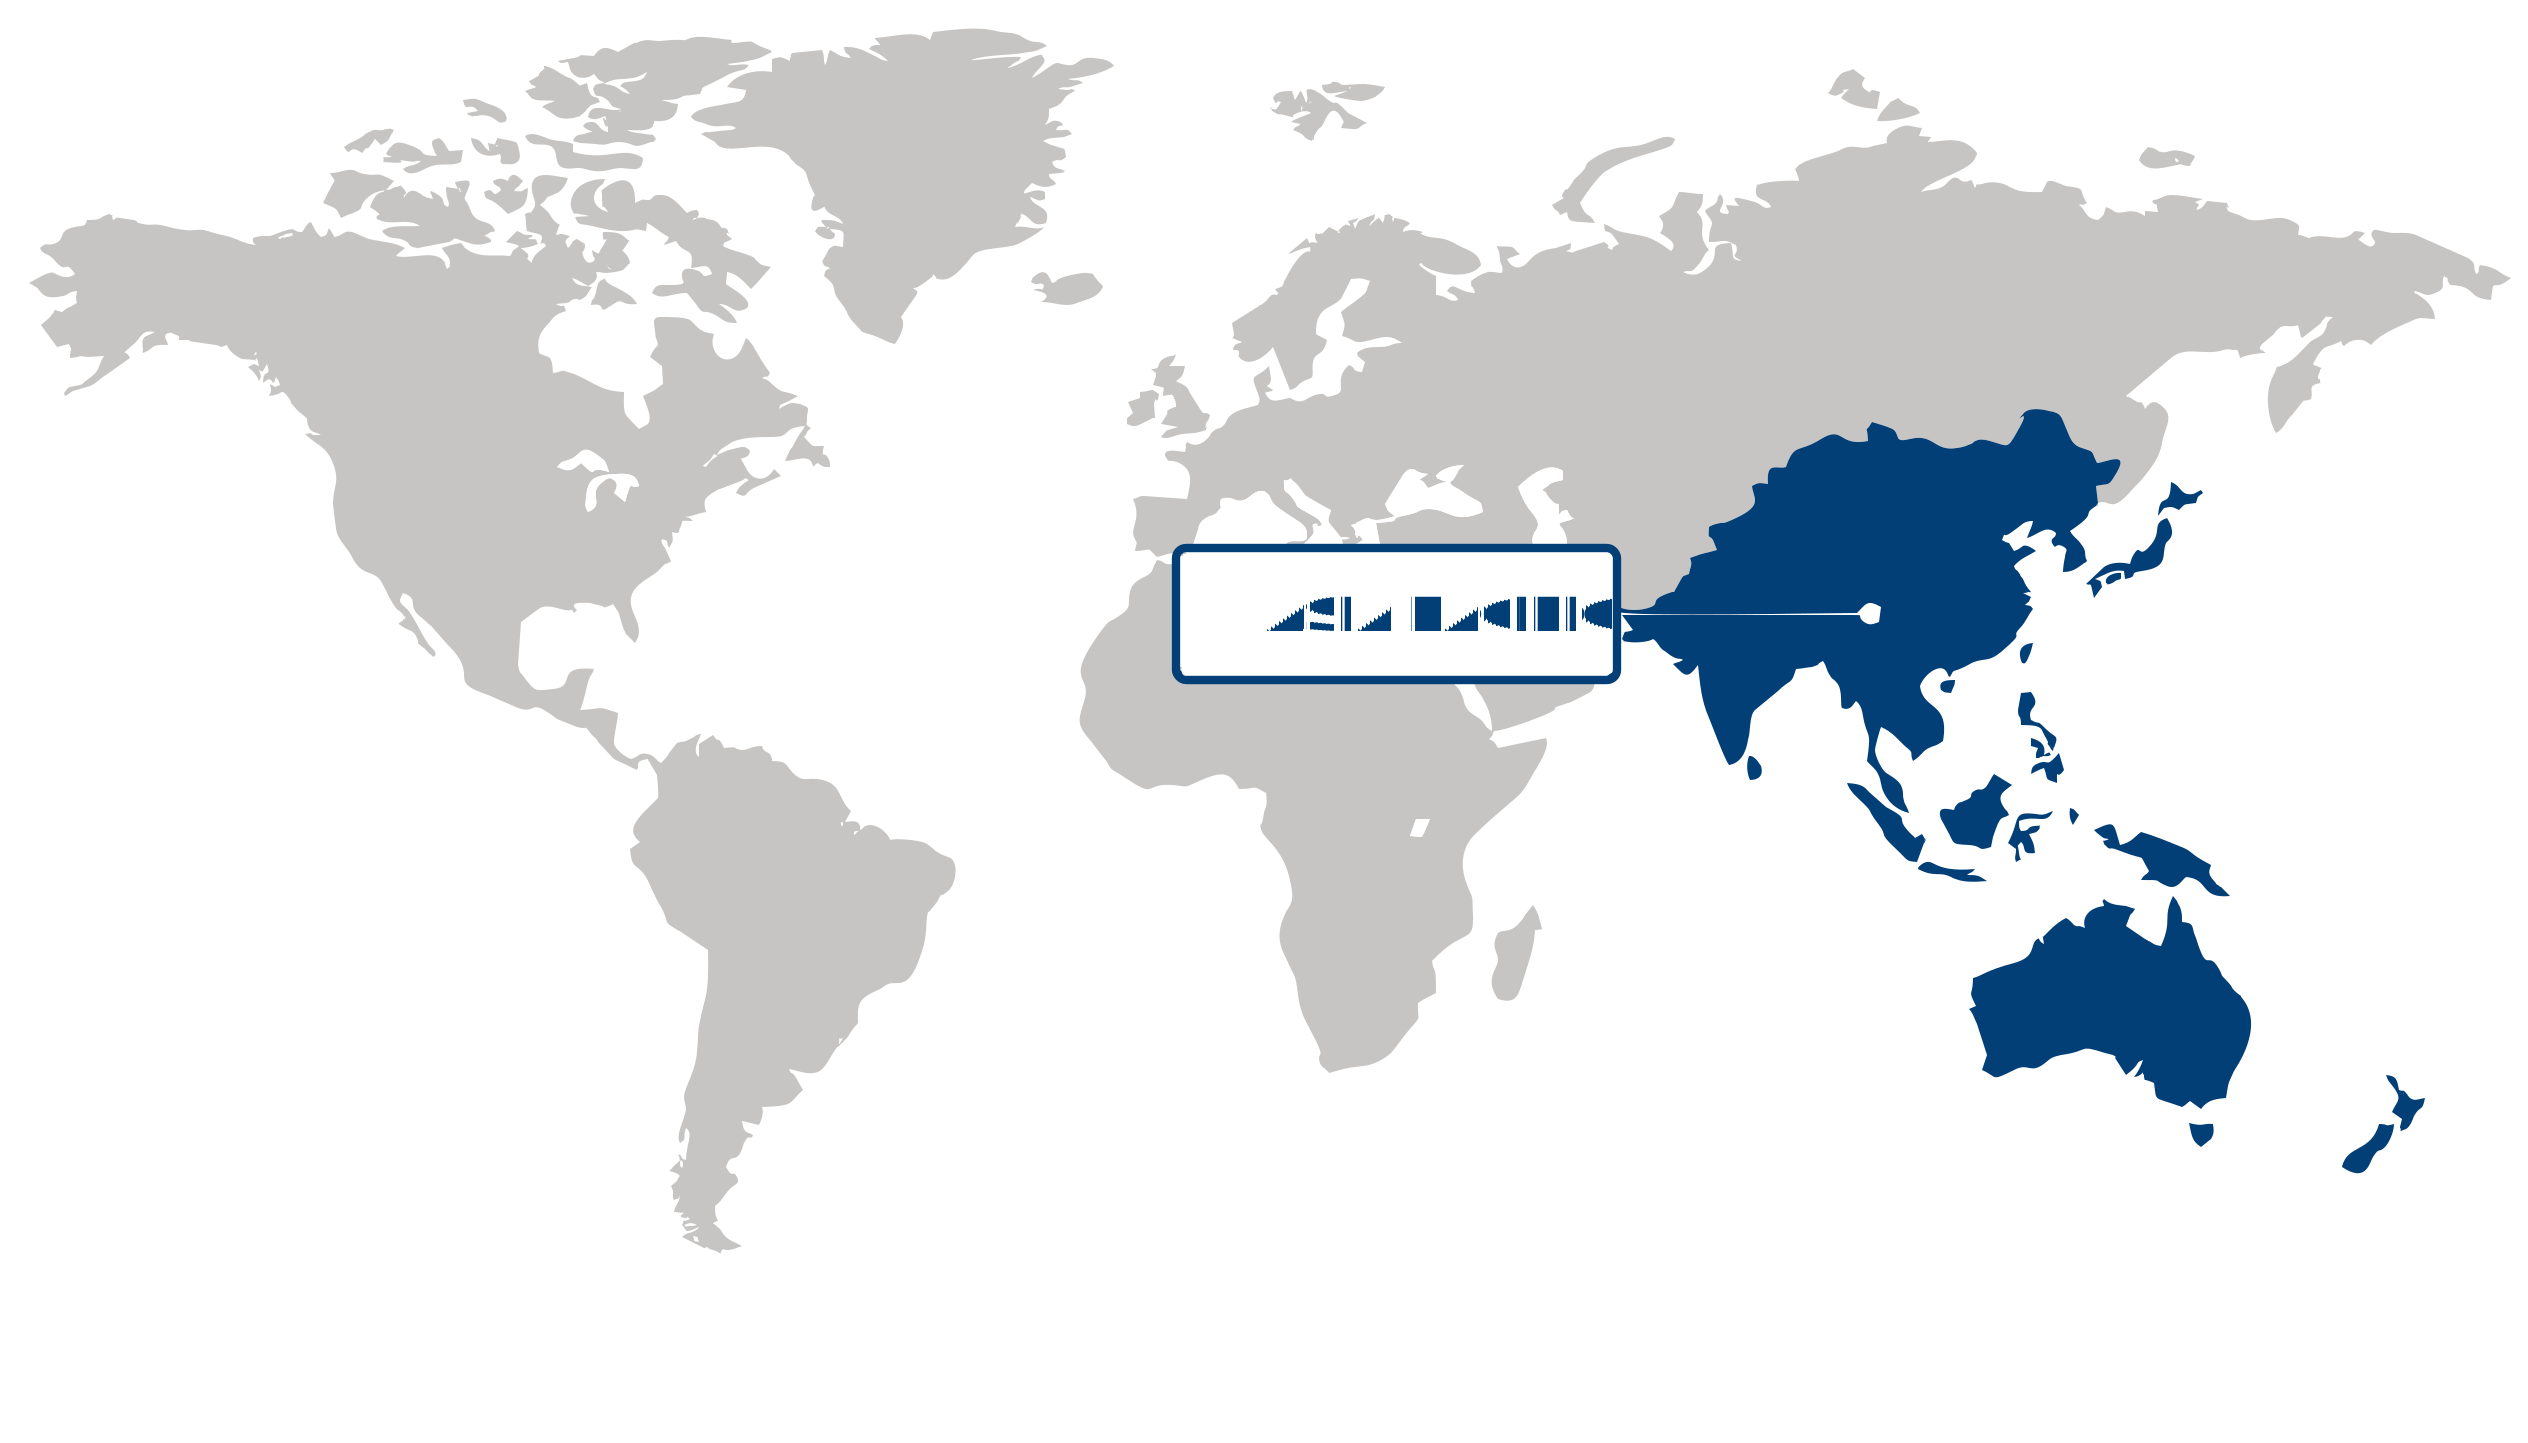
Asia Pacific (Largest & Fastest-Growing Region)
The EV platform market was led by Asia Pacific, which held a 37.8% share in 2026, while also representing the fastest-growing regional market. The region's strong position is supported by expanding electric mobility, established automotive manufacturing capabilities, and substantial investment in vehicle electrification. Growing demand for electric passenger and commercial vehicles is encouraging automakers and suppliers to develop scalable vehicle platforms that can support efficient production and flexible model development. Continued expansion of charging infrastructure, supportive electrification policies, and advances in battery and vehicle technologies are further strengthening the region's adoption of EV platforms.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
United States 🇺🇸
Scalable Platform InnovationThe U.S. emphasizes flexible EV platform architectures that support multiple vehicle segments and software-defined capabilities. Automakers in the U.S. continue aligning platform investments with battery integration, manufacturing efficiency, and evolving consumer demand for electric mobility.
Germany 🇩🇪
Premium Engineering IntegrationGermany prioritizes advanced EV platforms that combine precision engineering with premium vehicle performance. Automotive manufacturers in Germany are refining modular vehicle architectures to streamline production while accommodating diverse electrified model portfolios.
Japan 🇯🇵
Efficient Modular DevelopmentJapan focuses on compact, highly efficient EV platform development that enhances manufacturing flexibility and vehicle reliability. Japanese automakers continue optimizing shared architectures to balance electrification strategies across domestic and international vehicle programs.
South Korea 🇰🇷
Battery-Centric Platform DesignSouth Korea advances EV platform development through close integration of battery technologies, electronics, and digital vehicle systems. Manufacturers in South Korea are strengthening dedicated electric vehicle architectures to improve production consistency and support next-generation mobility solutions.
France 🇫🇷
Sustainable Mobility IntegrationFrance supports EV platform development through sustainable vehicle design and expanding electrification initiatives. Automotive companies in France increasingly adapt modular platforms that simplify production while meeting evolving environmental and consumer expectations.
Italy 🇮🇹
Performance Vehicle ElectrificationItaly is adapting EV platforms to preserve distinctive vehicle performance while supporting electrified model development. Manufacturers in Italy are integrating modular electric architectures across premium and specialty vehicle segments to broaden electrification capabilities.
EV Platform Market Share (%), by Vehicle, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportVehicle Segment Analysis: Passenger Cars (Largest Segment) vs Commercial Vehicles (Fastest-Growing Segment)
The EV platform market was led by the passenger cars segment, which accounted for 61.48% in 2026. The dominance of this segment is supported by strong consumer demand for electric passenger mobility, expanding model availability, and continuous investments by automakers in dedicated electric vehicle architectures. Governments' supportive policies, improving charging infrastructure, and growing awareness of sustainable transportation have further accelerated the deployment of passenger electric vehicles, reinforcing the segment's leading position.
The commercial vehicles segment is emerging as the fastest-growing category as fleet operators increasingly transition toward electrified transportation to reduce operating costs and comply with stricter emissions regulations. Rising adoption of electric buses, delivery vans, and medium- and heavy-duty commercial vehicles is encouraging manufacturers to develop scalable EV platforms capable of supporting higher payloads, longer driving ranges, and diverse commercial applications. Continued expansion of logistics and public transportation electrification initiatives is expected to sustain strong growth for this segment.
Sales Channel Segment Analysis: OEM (Largest & Fastest-Growing Segment)
The OEM sales channel dominated the EV platform market, capturing 83.3% in 2026 while also representing the fastest-growing segment. Original equipment manufacturers are increasingly investing in dedicated electric vehicle platforms to improve manufacturing efficiency, accelerate product development, and optimize vehicle performance across multiple models. Their direct involvement in platform design, battery integration, and software development enables greater quality control and technological innovation. As global automotive manufacturers continue expanding their electric vehicle portfolios, OEM-driven platform development remains the primary engine of market growth.
Propulsion Segment Analysis: Battery Electric Vehicles (BEV) (Largest & Fastest-Growing Segment)
Battery electric vehicles (BEV) represented the largest propulsion segment in 2026 while also recording the fastest growth within the EV platform market. The increasing preference for fully electric mobility, supported by advances in battery technology, improved driving range, and expanding charging infrastructure, continues to accelerate BEV adoption worldwide. Dedicated BEV platforms provide greater design flexibility, enhanced energy efficiency, and optimized vehicle packaging, making them the preferred choice for next-generation electric vehicles. Continued investment in electrification strategies and supportive regulatory frameworks further strengthen the segment's long-term leadership.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Vehicle | Passenger Cars, Commercial Vehicles | Passenger Cars | Commercial Vehicles |
| Sales Channel | OEM, Aftermarket | OEM | OEM |
| Propulsion | Battery Electric Vehicles (BEV), Hybrid Electric Vehicles (HEV), Plug-in Hybrid Electric Vehicles (PHEV) | Battery Electric Vehicles (BEV) | Battery Electric Vehicles (BEV) |
| Platform | P0, P1, P2, P3, P4 | P3 | P3 |
| Component | Battery, Suspension System, Motor System, Chassis, Electronic Control Units (ECUs), Others | Battery | Battery |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Major players in the EV platform market:
- Tesla, Inc. (United States)
- BYD Company Limited (China)
- Toyota Motor Corporation (Japan)
- Volkswagen AG (Germany)
- General Motors Company (United States)
- Ford Motor Company (United States)
- Hyundai Motor Company (South Korea)
- Stellantis N.V. (Netherlands)
- Rivian Automotive, Inc. (United States)
- NIO, Inc. (China)
The basis of competition is moving toward platform flexibility, allowing manufacturers to support multiple vehicle categories, battery configurations, and drivetrain architectures from a common engineering foundation while reducing development complexity. Modular design approaches are increasingly complemented by software-centric vehicle architectures, enabling continuous feature enhancements, improved energy management, and closer integration of advanced driver assistance and connected vehicle capabilities throughout the product lifecycle. Engineering priorities are also extending beyond vehicle performance to include manufacturing adaptability, scalable component integration, and streamlined validation processes that shorten development timelines across different regional requirements. As electrification strategies mature, competitive differentiation is becoming more dependent on architectural efficiency, software integration, and the ability to accommodate future technological upgrades without extensive platform redesign.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Tesla Inc. (United States) | |||||||
| BYD Company Limited (China) | |||||||
| Toyota Motor Corporation (Japan) | |||||||
| Volkswagen AG (Germany) | |||||||
| General Motors Company (United States) | |||||||
| Ford Motor Company (United States) | |||||||
| Hyundai Motor Company (South Korea) | |||||||
| Stellantis N.V. (Netherlands) | |||||||
| Rivian Automotive Inc. (United States) | |||||||
| NIO Inc. (China) |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| Ford | Aug-25 | Ford announced a major capital investment to launch its Universal EV Platform, which will underpin an affordable midsize electric pickup in 2027, optimizing manufacturing costs and driving the commercial scalability of its lower-cost EV portfolio. |
| Mahindra & Mahindra | Jun-25 | Mahindra & Mahindra announced the development of its modular "Nu" multi-energy architecture at its Mumbai facility, designed to simultaneously support internal combustion, hybrid, and electric vehicle platform configurations. |
| CATL | May-25 | CATL entered into a strategic partnership with Changan Mazda to co-develop battery electric vehicles utilizing its advanced Bedrock chassis platform, expanding its commercial platform-as-a-service market footprint. |
| Leapmotor | Apr-25 | Leapmotor finalized a supply agreement with FAW to provide its proprietary electric vehicle platform for Hongqi-branded EVs, expanding its cross-company platform commercialization into international markets. |
| Nissan | Apr-25 | Nissan unveiled plans for a scalable domestic EV platform supporting five upcoming U.S. models across the crossover, sedan, and lifestyle pickup segments, strengthening its long-term manufacturing footprint. |
| Stellantis | Sep-24 | Stellantis committed $406 million to upgrade three Michigan manufacturing facilities for the production of electric vehicles and next-generation EV platform components, enhancing regional manufacturing capacity and structural supply chain resilience. |
| Volkswagen | Jun-24 | Volkswagen announced the planned 2028 deployment of its unified SSP electric vehicle architecture, integrating advanced software, fast-charging capabilities, and autonomous driving readiness to redefine its competitive positioning. |
| Audi | May-24 | Audi established a strategic partnership with SAIC to co-develop a dedicated electric vehicle platform engineered specifically for the Chinese market, accelerating localized commercialization and product alignment. |
| Stellantis | Jan-24 | Stellantis introduced its flexible STLA Large platform architecture, designed to underpin eight upcoming multi-brand vehicles and support various high-performance powertrain configurations, including battery electric vehicles. |
| Tata Motors | Jan-24 | Tata Motors commercialized its new Acti.ev dedicated electric skateboard architecture, establishing a scalable foundation to support its upcoming EV portfolio, beginning with the launch of the Punch.ev model. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
EV Platform Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Vehicle Architecture | Skateboard Platform, Modular Platform, Dedicated EV Platform, Adapted ICE Platform |
| Manufacturing Model | In-house Manufacturing, Contract Manufacturing, Joint Development |
| Vehicle Price Tier | Economy, Mid-range, Premium, Luxury |
EV Platform Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| Platform Architecture Strategy |
|
| OEM Platform Consolidation |
|
| EV Platform Cost Optimization |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How large is the EV platform market?
What is the anticipated CAGR of the EV platform industry?
How are modular vehicle architectures transforming EV platform development?
Why is charging infrastructure expansion supporting EV platform standardization?
Why do passenger cars lead the EV platform market?
Why are commercial vehicles the fastest-growing vehicle segment in the EV platform market?
Why does Asia Pacific lead the EV platform market?
What makes Asia Pacific the fastest-growing region for EV platforms?
Who holds a significant market share in the EV platform landscape?
Our Clients
"The team surpassed our expectations with the report depth. The actionable insights provided proved crucial in navigating market challenges."
Tata Motors
"We found the report to be very informative. The expertise and attention to market nuances significantly influenced our business direction."
DENSO Corporation
"The consumer survey findings were quite good. We now have a clearer picture of the customer churning and retention strategy."
HL Mando
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Automotive & Transportation Research Team at Fundamental Business Insights, a dedicated research group specializing in the global automotive, mobility, and transportation industries. Our analysts continuously monitor vehicle technology advancements, electrification trends, autonomous and connected mobility, manufacturing developments, supply chain dynamics, regulatory standards, emissions policies, aftermarket activities, and evolving consumer and commercial transportation requirements to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with vehicle manufacturers, component suppliers, technology providers, distributors, logistics stakeholders, and industry experts, along with company annual reports, regulatory publications, government transportation statistics, industry associations, technical standards, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook