Automotive Embedded Telematics Market Size & Growth Forecast 2027–2036, By Segments (Application, Component, Solution), Regional Demand Trends (North America, Asia Pacific, Europe), Key Country Insights (U.S., Japan, South Korea, Germany, France, Italy), and Competitive Landscape
Jump to Content
Market Size and Growth Outlook
Automotive Embedded Telematics Market size was over USD 27.49 billion in 2026 and is likely to grow at a 17.67% CAGR between 2027 and 2036, attaining USD 139.9 billion by 2036. The industry revenue for 2027 is assessed at USD 31.58 billion.
Get more details on this report
Request Free Sample ReportAutomotive Embedded Telematics Market Intelligence Snapshot
Regional Market Dynamics
- Europe leads with 35.62% share due to mature connected vehicle ecosystem, strong OEM integration, and regulatory emphasis on safety, emissions monitoring, and embedded connectivity across vehicle platforms.
- Asia Pacific is growing at 20.83% CAGR driven by rising vehicle production, OEM-led integration of factory-fitted telematics, and increasing demand for navigation, diagnostics, and in-car connectivity.
Segment Momentum
- Passenger cars represented 71.52% of the market in 2026, driven by widespread integration of embedded connectivity for navigation, safety, diagnostics, and convenience features across personal vehicles.
- Commercial vehicles are the fastest-growing application segment as fleet operators increasingly use telematics to improve route efficiency, vehicle visibility, maintenance planning, and overall operational performance.
Market Expansion Drivers
- Rising integration of wireless connectivity and ADAS technologies enhancing vehicle safety systems.
- Increasing fleet management requirements driving adoption of embedded telematics in commercial vehicles.
- Stringent automotive safety regulations accelerating installation of connected telematics platforms.
Leading Market Participants
- Prominent companies in the automotive embedded telematics market include Ford Motor Company (United States), Continental AG (Germany), General Motors Company (United States), TomTom Telematics BV (Netherlands), Hyundai Motor Company (South Korea), Toyota Motor Corporation (Japan), MiX Telematics International Ltd. (South Africa), INFINITI Motor Company Ltd. (Japan), BMW Group (Germany), Verizon Connect (United States).
Global Market Forecast Snapshot
Market Outlook
- 2026 Market Size: USD 27.49 billion
- 2027 Estimated Market Size: USD 31.58 billion.
- Projected Market Size: USD 139.9 billion by 2036
- Growth Forecast: 17.67% CAGR (2027-2036)
Regional and Segment Outlook
- Leading Regional Market: Europe
- High-Growth Regional Hub: Asia Pacific
- Core Revenue Segment: Passenger Cars (Application) | Services (Component) | Safety & Security (Solution)
- Emerging Opportunity Segment: Commercial Vehicles (Application) | Services (Component) | Remote Diagnostics (Solution)
Market Growth Drivers and Industry Trends
Rising integration of wireless connectivity and ADAS technologies enhancing vehicle safety systems
Modern vehicles are increasingly combining wireless communication capabilities with advanced driver assistance functions to improve situational awareness and vehicle safety. The automotive embedded telematics market is supported by this integration because embedded systems can facilitate communication between vehicles, networks, onboard electronics, and safety-related functions. Connectivity enables the transmission of vehicle information and supports services such as remote diagnostics, navigation, emergency assistance, and real-time operational monitoring. As ADAS architectures become more sophisticated, embedded telematics platforms are increasingly being incorporated to manage connected vehicle information alongside safety and driver-support applications.
Increasing fleet management requirements driving adoption of embedded telematics in commercial vehicles
Commercial fleet operators are seeking greater visibility into vehicle location, utilization, fuel or energy consumption, maintenance requirements, and driver behavior. This shift is strengthening the automotive embedded telematics market as integrated systems provide continuous vehicle data that can support centralized fleet monitoring and operational decision-making. Embedded telematics allows fleet managers to track vehicles remotely, optimize routes, identify maintenance needs, and evaluate vehicle performance across distributed operations. The growing emphasis on asset utilization and operational efficiency is encouraging commercial vehicle operators to incorporate connected telematics into fleet management strategies.
Stringent automotive safety regulations accelerating installation of connected telematics platforms
Increasing regulatory attention to vehicle safety and connected safety functions is encouraging automakers to incorporate more sophisticated electronic systems into new vehicles. Within the automotive embedded telematics market, regulatory requirements can accelerate adoption of platforms that support emergency communication, vehicle monitoring, diagnostics, and safety-related connectivity. Embedded systems provide an integrated foundation for transmitting critical vehicle information and supporting communication between onboard systems and external networks. As vehicle safety architectures become more digitally connected, manufacturers are increasingly incorporating telematics capabilities as part of broader compliance and vehicle functionality requirements.
| Growth Driver | Impact on CAGR | Regulatory Influence | Geographic Relevance | Adoption Rate | Impact Timeline |
|---|---|---|---|---|---|
| Rising integration of wireless connectivity and ADAS technologies enhancing vehicle safety systems | 2.00% | High | North America, Europe | High | Near Term |
| Increasing fleet management requirements driving adoption of embedded telematics in commercial vehicles | 1.70% | Moderate | Asia Pacific, North America | High | Mid Term |
| Stringent automotive safety regulations accelerating installation of connected telematics platforms | 1.50% | High | Europe, North America | Emerging | Mid Term |
Explore Growth Opportunities
Request Free Sample ReportRegional Demand Dynamics
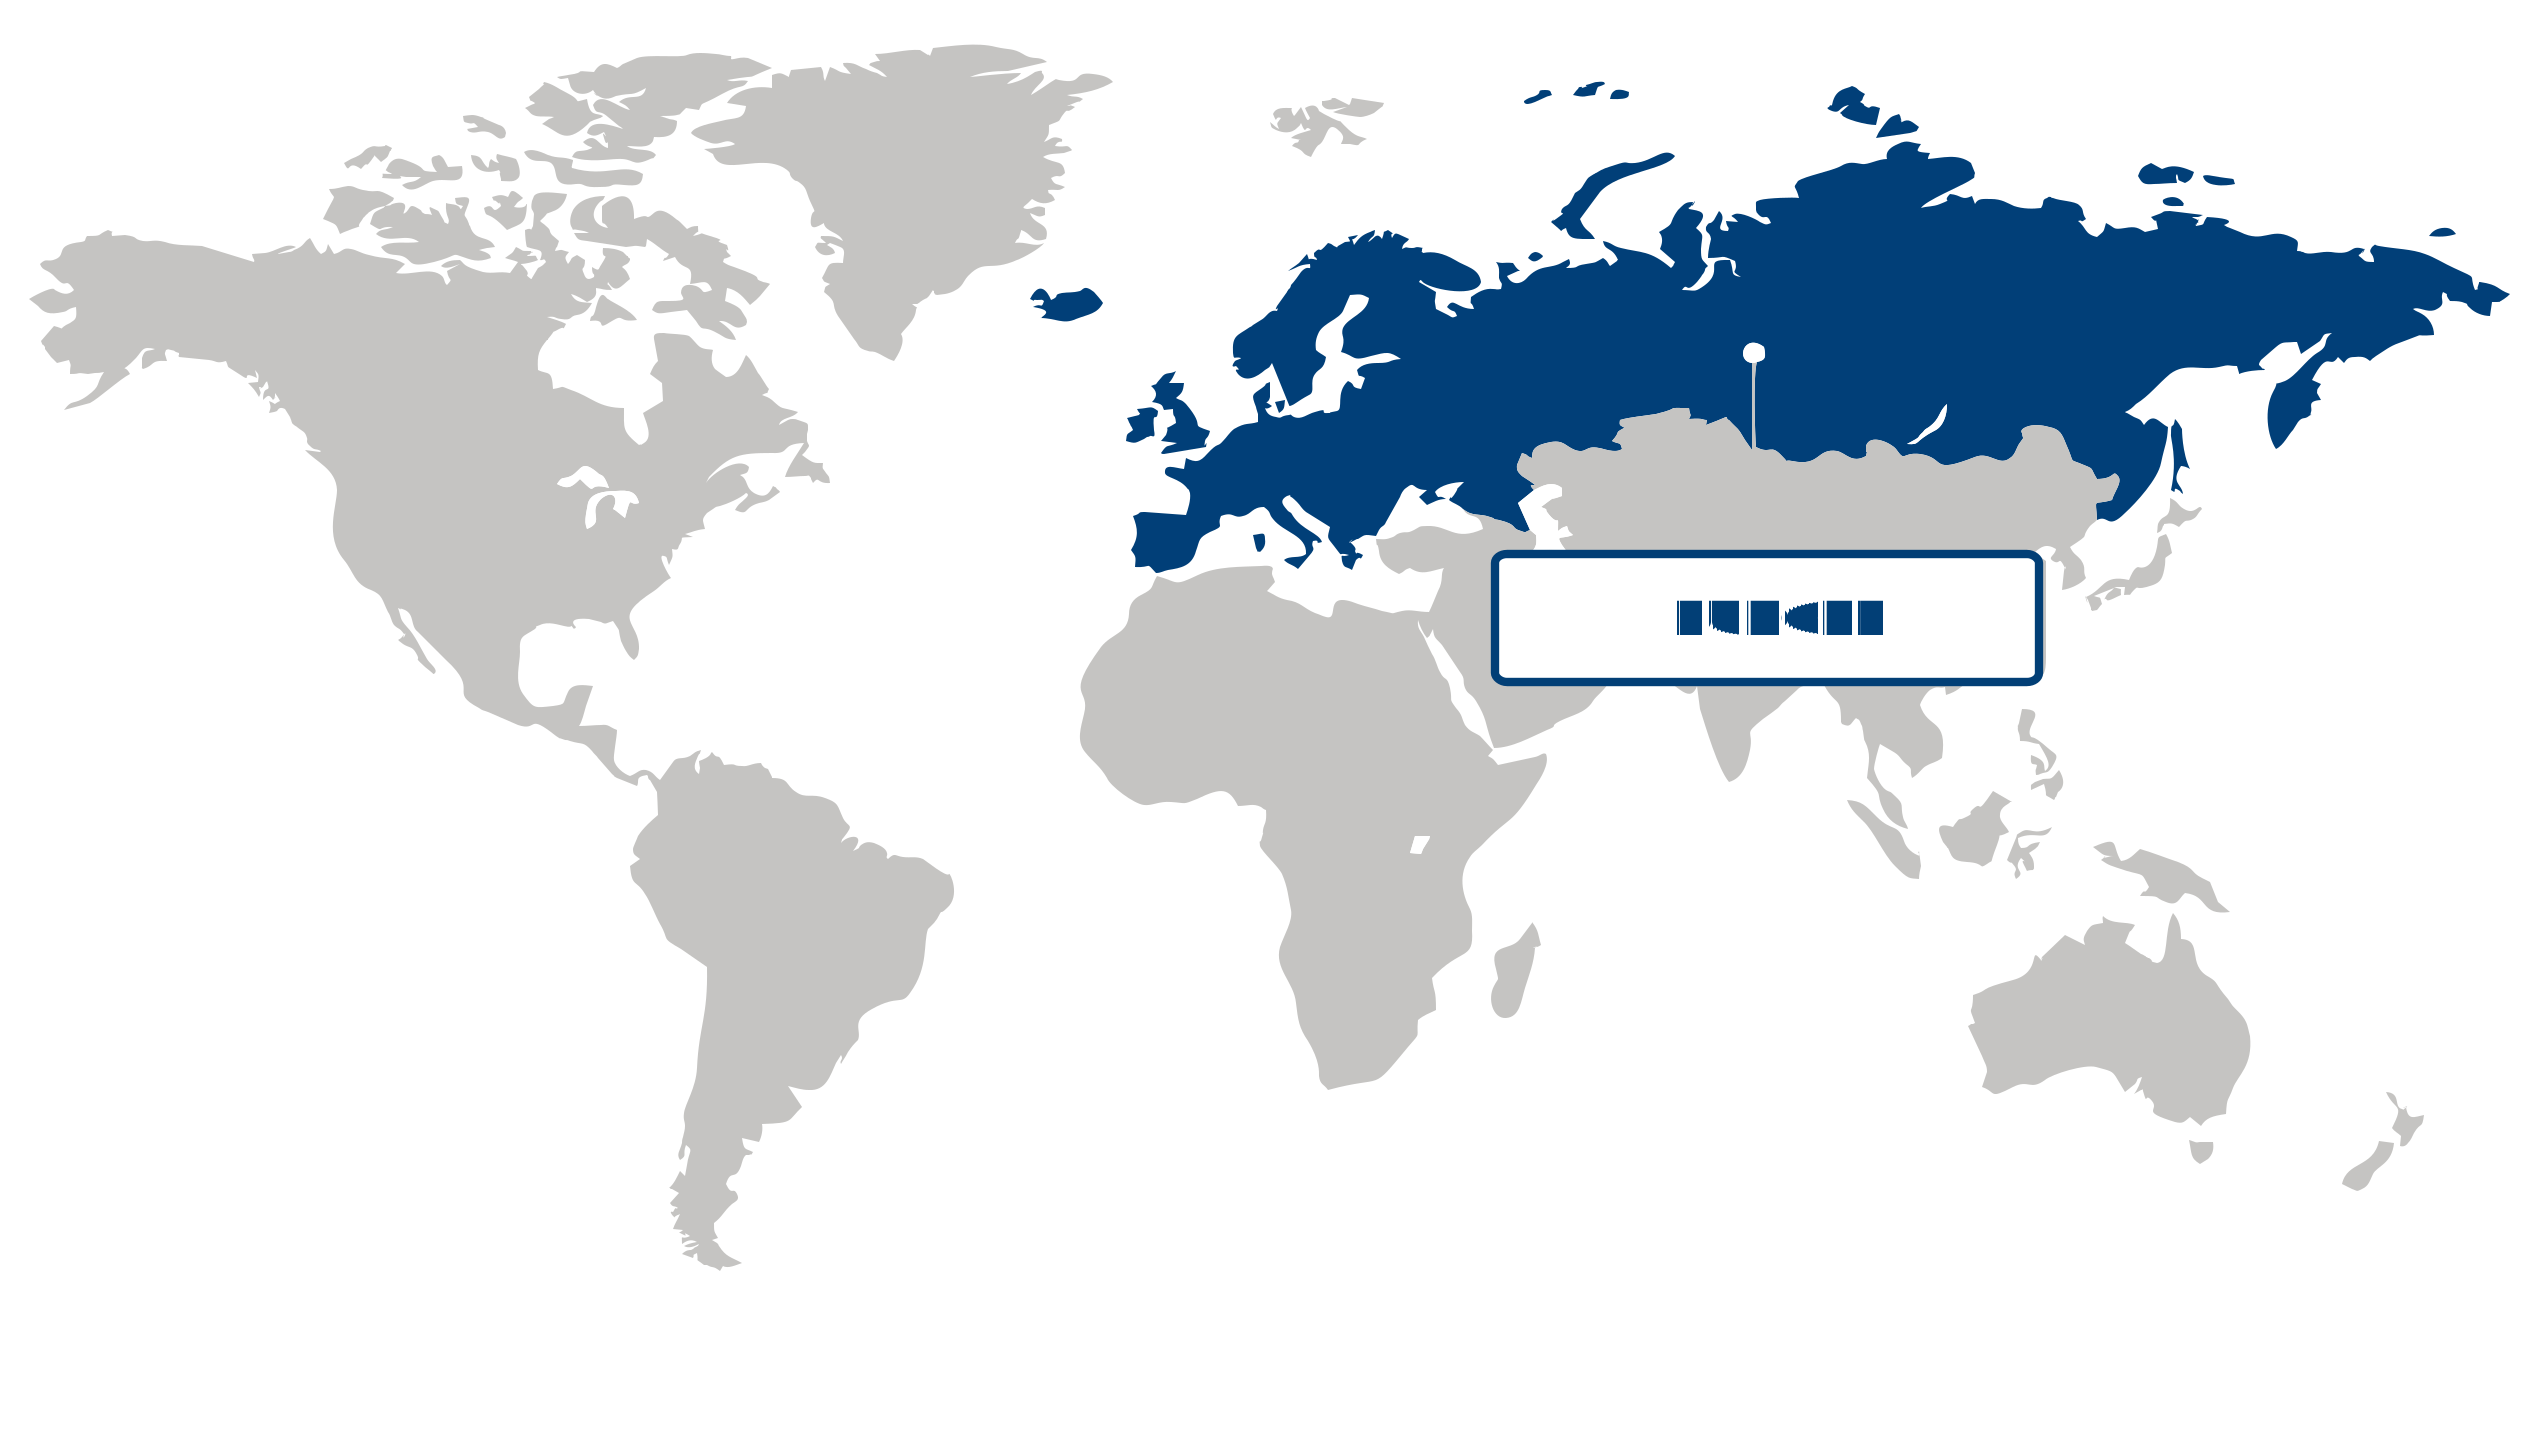
Europe (Largest Region)
In the automotive embedded telematics market, Europe held the largest share of 35.62% in 2026, reflecting the region's mature automotive industry and strong adoption of connected vehicle technologies. Demand is supported by increasing integration of navigation, vehicle diagnostics, safety functions, and real-time connectivity into modern vehicles. The region's focus on road safety, vehicle efficiency, intelligent mobility, and digitally connected transportation systems is encouraging automakers to expand the use of embedded telematics across passenger and commercial vehicle applications.
Asia Pacific (Fastest-Growing Region)
Asia Pacific is the fastest-growing region, supported by expanding vehicle production, rising consumer interest in connected mobility, and increasing deployment of advanced automotive electronics. Rapid urbanization and the need for improved transportation efficiency are encouraging greater use of vehicle connectivity and data-enabled services. Growing investment in automotive technology, expanding digital infrastructure, and increasing adoption of intelligent and connected vehicles are creating favorable conditions for embedded telematics solutions across the region.
| Parameter | North America | Asia Pacific | Europe | Latin America | MEA |
|---|---|---|---|---|---|
| Innovation HubiScaleNascentDeveloping Advanced | |||||
| Cost-Sensitive RegioniScaleLowMedium High | |||||
| Regulatory EnvironmentiScaleRestrictiveNeutral Supportive | |||||
| Demand DriversiScaleWeakModerate Strong | |||||
| Development StageiScaleEmergingDeveloping Developed | |||||
| Adoption RateiScaleLowMedium High | |||||
| New Entrants / StartupsiScaleSparseModerate Dense | |||||
| Macro IndicatorsiScaleWeakStable Strong |
Key Country Insights
Germany 🇩🇪
Premium Vehicle ConnectivityGermany prioritizes embedded telematics that support connected mobility, predictive maintenance, and advanced vehicle functionality. Automotive manufacturers in Germany continue integrating secure communication platforms with intelligent vehicle systems to enhance customer experience and operational efficiency.
France 🇫🇷
Mobility Services IntegrationFrance continues expanding embedded telematics by supporting connected mobility services, fleet optimization, and intelligent transportation solutions. Automotive stakeholders in France increasingly integrate vehicle connectivity with digital service ecosystems to improve operational visibility and customer engagement.
Italy 🇮🇹
Fleet Connectivity AdoptionItaly is increasing adoption of embedded telematics across passenger and commercial vehicles with a growing focus on fleet efficiency and connected mobility. Automotive companies in Italy continue integrating digital communication technologies that support vehicle monitoring, maintenance, and operational management.
Japan 🇯🇵
Intelligent Vehicle SystemsJapan continues advancing embedded telematics through strong integration of connected technologies within passenger and commercial vehicles. Automotive companies in Japan emphasize reliable communication platforms that support navigation, safety applications, and vehicle lifecycle management.
South Korea 🇰🇷
Software-Driven ConnectivitySouth Korea is strengthening automotive embedded telematics through connected vehicle platforms and software-defined mobility initiatives. Vehicle manufacturers in South Korea increasingly integrate cloud connectivity, remote diagnostics, and digital services to enhance user experience and operational capabilities.
United States 🇺🇸
Connected Mobility InnovationThe U.S. continues expanding automotive embedded telematics through increasing demand for connected vehicle services, fleet management, and remote diagnostics. Automotive manufacturers in the U.S. are integrating advanced connectivity features that enhance vehicle performance, safety, and digital service delivery.
Automotive Embedded Telematics Market Share (%), by Application, 2026
Go beyond the chart, access full insights & data tables
Request Free Sample ReportApplication Segment Analysis: Passenger Cars (Largest Segment) vs Commercial Vehicles (Fastest-Growing Segment)
Passenger cars held the leading position in the automotive embedded telematics market, accounting for a 71.52% share in 2026, supported by increasing integration of connected technologies for navigation, vehicle diagnostics, safety, infotainment, and remote monitoring. Growing consumer expectations for connected driving experiences are encouraging automakers to incorporate telematics capabilities into passenger vehicles, while rising interest in vehicle personalization and real-time information services further supports adoption. The expansion of connected mobility ecosystems is also strengthening the role of embedded telematics in improving convenience and vehicle management.
Commercial vehicles are emerging as the fastest-growing application as fleet operators increasingly rely on connected systems to improve vehicle utilization, monitor operating conditions, and optimize transportation activities. Embedded telematics enables more effective fleet visibility, maintenance planning, route management, and driver monitoring, making it increasingly valuable for logistics and transportation operations. The broader shift toward data-driven fleet management and connected commercial mobility is supporting greater integration of telematics across trucks, delivery vehicles, and other business-oriented vehicle fleets.
Component Segment Analysis: Services (Largest & Fastest-Growing Segment)
The services segment dominated the automotive embedded telematics market with a 53.97% share in 2026 and is also the fastest-growing component, reflecting the increasing importance of software-enabled connectivity and ongoing digital services within vehicles. Telematics services support functions such as vehicle tracking, diagnostics, navigation, emergency assistance, and remote vehicle management, creating continuing value beyond the initial installation of embedded hardware. As connected vehicles generate greater volumes of operational data, demand for cloud connectivity, analytics, subscription-based services, and continuous software enhancements is strengthening the segment's market position.
| Segment | Sub-Segment | Largest Segment | Fastest Growing |
|---|---|---|---|
| Application | Passenger Cars, Commercial Vehicles | Passenger Cars | Commercial Vehicles |
| Component | Hardware, Services, Connectivity | Services | Services |
| Solution | Safety & Security, Information & Navigation, Entertainment, Remote Diagnostics | Safety & Security | Remote Diagnostics |
Unlock insights tailored to your business with our bespoke market research solutions.
Click to get your customized report now.
Competitive Landscape and Market Positioning
Prominent players in the automotive embedded telematics market:
1. Ford Motor Company (United States)
2. Continental AG (Germany)
3. General Motors Company (United States)
4. TomTom Telematics BV (Netherlands)
5. Hyundai Motor Company (South Korea)
6. Toyota Motor Corporation (Japan)
7. MiX Telematics International Ltd. (South Africa)
8. INFINITI Motor Company Ltd. (Japan)
9. BMW Group (Germany)
10. Verizon Connect (United States)
The automotive embedded telematics market is evolving through increased integration of AI-enabled connectivity platforms, real-time vehicle diagnostics, and IoT-based communication systems. Industry participants are strengthening collaborations with mobility technology providers to enhance navigation, fleet monitoring, and in-vehicle digital services. Consolidation activities and capability expansion initiatives are further supporting the development of advanced telematics ecosystems tailored for connected and autonomous mobility solutions.
| Company | Market Share | Company Revenue | Revenue CAGR (%) | Product Portfolio | Geographic Presence | Innovation / R&D Focus | Strategic Developments |
|---|---|---|---|---|---|---|---|
| Ford Motor Company (United States) | |||||||
| Continental AG (Germany) | |||||||
| General Motors Company (United States) | |||||||
| TomTom Telematics BV (Netherlands) | |||||||
| Hyundai Motor Company (South Korea) | |||||||
| Toyota Motor Corporation (Japan) | |||||||
| MiX Telematics International Ltd. (South Africa) | |||||||
| INFINITI Motor Company Ltd. (Japan) | |||||||
| BMW Group (Germany) | |||||||
| Verizon Connect (United States). |
Industry Development/News
| Company Name | Date | Key Development |
|---|---|---|
| CerebrumX Labs Inc. | Dec-22 | Collaborated with Toyota to use embedded telematics data from connected network vehicles to generate real-time fleet insights and lower the Total Cost of Ownership (TCO). |
| CerebrumX Labs Inc. | Nov-22 | Integrated connected vehicle data from Ford and Lincoln vehicles into its data-focused usage-based insurance (UBI)-as-a-Service platform to assist insurance providers. |
| Hitachi Solutions | Apr-22 | Collaborated with BitBrew to merge its connected vehicle platform with Hitachi's enterprise and insurance expertise, providing real-time streams for vehicle health and driver behavior analysis. |
| Geotab Inc. | Mar-22 | Collaborated with Stellantis subsidiary Free2move to integrate embedded vehicle telematics from brands like Jeep, Ram, Dodge, and Chrysler directly into the MyGeotab dashboard. |
Customize Your Report
Explore examples of how this report can be tailored to different research needs, including custom segments, additional topics or chapters, and related reports. Click a section of the wheel or its numbered marker to explore the available options.
Automotive Embedded Telematics Market — Custom Segments
| Segment | Sub-Segment |
|---|---|
| Propulsion Type | Internal Combustion Engine Vehicles, Hybrid Electric Vehicles, Battery Electric Vehicles, Plug-in Hybrid Electric Vehicles |
| Vehicle Ownership | Privately Owned Vehicles, Fleet-Owned Vehicles, Leased Vehicles, Rental Vehicles |
| Subscription Model | Subscription-Based, Pay-Per-Use, Bundled with Vehicle Purchase, Free/Manufacturer-Supported |
Automotive Embedded Telematics Market — Custom TOC
| Custom Chapter | Chapter Details |
|---|---|
| OEM Connectivity Strategy Benchmarking |
|
| Telematics Service Monetization Models |
|
| Embedded Connectivity Migration Outlook |
|
Need a different cut of the data?
Request Custom ResearchFrequently Asked Questions
How much is the automotive embedded telematics market worth?
What is the expected industry size of automotive embedded telematics by 2036?
How are fleet management priorities influencing adoption of embedded telematics systems?
Why are automotive safety regulations accelerating deployment of embedded telematics platforms?
Why do passenger cars account for the largest share of the automotive embedded telematics market?
What is driving rapid growth in commercial vehicle telematics adoption?
Why does Europe lead the automotive embedded telematics market?
What is driving Asia Pacific growth in automotive embedded telematics market?
What are the key competitors in the automotive embedded telematics landscape?
Our Clients
"The team surpassed our expectations with the report depth. The actionable insights provided proved crucial in navigating market challenges."
Tata Motors
"We found the report to be very informative. The expertise and attention to market nuances significantly influenced our business direction."
DENSO Corporation
"The consumer survey findings were quite good. We now have a clearer picture of the customer churning and retention strategy."
HL Mando
Our Research Team & Methodology
Every Fundamental Business Insights report is built by a dedicated vertical research team, validated through a structured primary-and-secondary methodology, and reviewed for accuracy before it reaches you.
This report was prepared by the Automotive & Transportation Research Team at Fundamental Business Insights, a dedicated research group specializing in the global automotive, mobility, and transportation industries. Our analysts continuously monitor vehicle technology advancements, electrification trends, autonomous and connected mobility, manufacturing developments, supply chain dynamics, regulatory standards, emissions policies, aftermarket activities, and evolving consumer and commercial transportation requirements to deliver timely and reliable market intelligence. The research is developed using a structured methodology that combines primary discussions with vehicle manufacturers, component suppliers, technology providers, distributors, logistics stakeholders, and industry experts, along with company annual reports, regulatory publications, government transportation statistics, industry associations, technical standards, and other authoritative secondary sources. Market estimates are validated through multiple research techniques, including top-down and bottom-up analysis, before undergoing an internal quality review to ensure accuracy, consistency, and methodological integrity prior to publication.
Delivery
Published
Available
Support
- Market Size & Forecast
- Market Segmentation
- Regional Analysis
- Growth Drivers & Challenges
- Market Dynamics
- Competitive Landscape
- Company Profiles
- Competitive Benchmarking
- Mergers & Acquisitions
- Market Share Analysis or Key Company Strategies
- Value Chain Analysis
- Porter's Five Forces
- PESTLE Analysis
- Pricing Trends
- Supply-Demand Analysis
- Technology Landscape
- Regulatory Landscape
- Investment & Funding Landscape
- Emerging Opportunities
- Future Market Outlook